- EMI is one fixed monthly payment that clears both principal and interest over the tenure. It is calculated on the reducing balance: interest is charged on what is still owed, not on the original amount.
- The formula is EMI = P × r × (1+r)n ÷ ((1+r)n − 1), where r = annual rate ÷ 12 ÷ 100 and n = months.
- Worked: ₹30,00,000 at 8.5% for 20 years = ₹26,035 a month and ₹32,48,327 of interest — 1.08 times the amount borrowed.
- Tenure is the bigger lever, not the rate. Stretching that loan from 15 to 30 years cuts the EMI by ₹6,475 and adds ₹29,86,672 of interest.
- Prepayment: ₹1,00,000 paid in month 1 of a ₹30L / 9% / 20-year loan saves ₹4,53,921 if you keep the EMI and shorten the tenure, or ₹1,15,934 if you cut the EMI instead.
- No prepayment charge applies to any floating-rate loan to an individual for non-business use sanctioned on or after 1 January 2026 (RBI, 2 July 2025). Fixed-rate loans can still carry one.
- A rate reset is a choice, not an order. A 1% hike handled by extending tenure adds 3 years and ₹16.92 lakh; the same hike absorbed as a higher EMI adds ₹5.86 lakh.
- The calculator stops at principal + interest. On ₹50L, a 0.5% processing fee plus 18% GST is ₹29,500 upfront and turns 8.50% into an 8.58% effective cost.
What EMI is — and the 3 myths around it
One fixed monthly number, two moving parts, and three pieces of advice that are repeated everywhere and are wrong.
EMI stands for Equated Monthly Instalment. It is the fixed amount you pay each month until the loan closes. Each payment carries interest on the balance outstanding that month, and principal, which is whatever is left of the payment. Because the balance falls, the interest share falls with it and the principal share rises — even though the total never changes.
The method is the same for a home, car, personal, education or gold loan. Only three things change: the amount, the rate, and the tenure. A fourth thing changes the answer without appearing in any calculator: what the lender does when the rate resets (section 15).
Fixed payment, falling balance
The EMI is constant. The split is not: month 1 of a ₹30L / 8.5% / 20-year loan is ₹21,250 interest and ₹4,785 principal. Month 143 is the first month principal wins.
Interest is charged on what is left
Not on the amount you borrowed. That one sentence separates reducing balance from flat rate, and it is worth 82% more interest on a 5-year loan (section 3).
Tenure decides the total
The rate sets the price per year. Tenure sets how many years you pay it. On a ₹30L loan, 15 years costs ₹23.18L in interest; 30 years costs ₹53.04L.
Three pieces of advice that are wrong
| What you read elsewhere | Why it fails | The correct number |
|---|---|---|
| “Early EMIs are mostly interest, so the split evens out in 3–4 years.” | Crossover timing depends almost entirely on tenure. Short loans start principal-heavy; long loans stay interest-heavy for a decade. | ₹5L at 10% for 5 years: principal beats interest in month 1. ₹30L at 8.5% for 20 years: month 143. |
| “A lower EMI is a cheaper loan.” | The EMI measures the size of the monthly hole, not the size of the debt. A longer tenure shrinks the hole and grows the debt. | ₹30L at 8.5%: 15 years = ₹29,542/month, ₹23.18L interest. 30 years = ₹23,067/month, ₹53.04L interest. |
| “Use the Rule of 72 to estimate total loan cost.” | The Rule of 72 compounds a lump sum left alone. A loan does the opposite: the balance shrinks every month, so the rule overstates the cost. | ₹10L at 10% for 20 years costs 2.32× the principal, not 2.8×. Use the formula or a schedule, not a doubling rule. |
Never compare two offers by EMI. Compare total payment (EMI × months) and effective cost (total interest plus fees, against the money you actually receive). Two loans with the same EMI can differ by lakhs, and two loans with the same rate can differ by more once fees and GST are added.
The formula, one worked example, and its limits
The annuity formula in plain language — then the five things it does not include, which is where most borrowers get surprised.
This is the reducing-balance formula, also called the annuity formula. Every EMI calculator, every bank sanction letter and every spreadsheet in this guide uses it. It assumes interest is charged once a month on the balance at the start of that month (monthly rest), the rate never changes, and you never pay anything extra.
P — Principal Loan Amount
This is the total amount you borrow from the lender. For a home loan of ₹50,00,000, P = 500000. If you make a down payment, the principal is reduced by that amount. For example, a ₹60 lakh home with ₹10 lakh down payment has a principal of ₹50 lakh.
r — Monthly Interest Rate
Banks quote interest rates annually, but EMI is calculated monthly. Divide the annual rate by 12 and then by 100. For example, if the annual interest rate is 10%, the monthly rate is 10 ÷ 12 ÷ 100 = 0.008333. This small decimal is what drives the interest calculation each month.
n — Total Number of Monthly Payments
This is the loan tenure expressed in months. A 5-year loan has n = 60 (5 x 12). A 20-year home loan has n = 240. A longer tenure means more payments but a lower EMI — however, you end up paying more total interest.
Worked Example: ₹5,00,000 Loan at 10% for 5 Years
- P = 5,00,000
- r = 10 ÷ 12 ÷ 100 = 0.008333
- n = 5 × 12 = 60 months
- (1+r)n = (1.008333)60 = 1.64531
- EMI = 500000 × 0.008333 × 1.64531 ÷ (1.64531 − 1)
- EMI = 6855.45 ÷ 0.64531 = ₹10,624
You pay ₹10,624 per month for 60 months. Total payment = ₹6,37,411. Total interest = ₹1,37,411 — about 21.6% of your total payment is the cost of borrowing.
What the formula leaves out
The EMI is the loan cost. It is not the borrowing cost. Five things sit outside the number on your calculator, and every one of them is real money.
| Left out | Where it hits | Typical size |
|---|---|---|
| Processing fee + GST | Deducted before disbursal, so you borrow more than you receive | 0.25–2% of the loan, plus 18% GST on the fee |
| Legal, valuation, stamp, CERSAI | Upfront, per property or per document | ₹5,000–₹30,000 on a home loan, state-dependent |
| Insurance | Annual premium, or bundled into the EMI | Often presented as mandatory; usually optional |
| Prepayment and rate resets | The schedule assumes a frozen rate and no extra payments | A 1% reset taken as tenure extension: ₹16.92L on a ₹50L loan (section 15) |
| Day-count convention | A few lenders compute interest daily, not monthly | Small per month, visible across 240 months |
The APR (annualised rate, which must include fees), the reset clause (what happens to EMI and tenure when the benchmark moves) and the prepayment clause. If any of the three is missing, ask for it in writing before you sign.
Flat rate vs reducing balance
Two ways to charge interest, and a table that converts the flat rate a dealer quotes into the rate your bank would quote.
Reducing balance charges interest on the balance; flat rate charges it on the original amount. Flat rate is common in car showroom finance, consumer durables and some personal loans, and it is not a scam — it is simply a different unit. The problem is that it is quoted the same way, so 10% flat looks like 10% reducing when it is really 17–18%.
| Feature | Reducing Balance | Flat Rate |
|---|---|---|
| Interest calculated on | Outstanding balance (decreases monthly) | Original principal (constant) |
| Total interest paid | Lower | Significantly higher |
| Used by | Most banks for home, car, education loans | Some personal loans, used car loans |
| Effective rate | Same as quoted rate | 1.6–1.9× the quoted rate (see the conversion table below) |
| Transparency | Standard, widely understood | Can be misleading |
Worked comparison: A ₹5,00,000 loan at 10% for 5 years:
| Method | Monthly EMI | Total Interest | Total Payment |
|---|---|---|---|
| Reducing Balance | ₹10,624 | ₹1,37,411 | ₹6,37,411 |
| Flat Rate | ₹12,500 | ₹2,50,000 | ₹7,50,000 |
The gap is not small. On the same ₹5L, the flat-rate loan costs ₹1,12,589 more in interest — 82% more, for the same “10%”.
Flat rate to the rate your bank quotes
This is the conversion table most calculators do not show. It solves for the reducing-balance rate that produces the same cash flows as the flat rate — the number you should actually compare.
| Quoted flat rate | True rate, 3-year loan | True rate, 5-year loan | True rate, 7-year loan |
|---|---|---|---|
| 8% | 14.5% | 14.1% | 13.7% |
| 9% | 16.2% | 15.7% | 15.2% |
| 10% | 17.9% | 17.3% | 16.7% |
| 11% | 19.6% | 18.8% | 18.1% |
| 12% | 21.2% | 20.3% | 19.5% |
Ask: “Is this rate flat or reducing balance, and what is the APR?” A lender quoting flat rate will rarely volunteer the conversion. If the answer is “flat”, add roughly 7 percentage points for a 5-year loan before you compare it with a bank offer. The shorter the tenure, the bigger the penalty.
Same ₹10 lakh, only the tenure changes
Loan-type tables quote rates that go stale every quarter. This one holds the rate fixed at 9% and changes only the tenure — which is what loan type actually decides.
| Tenure | EMI on ₹10L at 9% | Total interest | Interest as a multiple of the loan |
|---|---|---|---|
| 1 year (gold loan) | ₹87,451 | ₹49,418 | 0.05× |
| 3 years (personal loan) | ₹31,800 | ₹1,44,790 | 0.14× |
| 5 years (car loan) | ₹20,758 | ₹2,45,501 | 0.25× |
| 7 years (used car, consumer) | ₹16,089 | ₹3,51,483 | 0.35× |
| 10 years (education, personal) | ₹12,668 | ₹5,20,109 | 0.52× |
| 15 years (home) | ₹10,143 | ₹8,25,680 | 0.83× |
| 20 years (home) | ₹8,997 | ₹11,59,342 | 1.16× |
| 30 years (home) | ₹8,046 | ₹18,96,641 | 1.90× |
Read the two outer columns together. From 1 year to 30 years the EMI falls by 91%, while the interest you pay rises 38 times. No rate negotiation in the market can produce a swing that large. That is why the loan type matters: it silently fixes your tenure before you ever discuss the rate.
Never borrow short-term money for a long-term asset or long-term money for a short-lived one. A 7-year loan on a car that is worth half its price in year 4 is how people end up owing more than the asset is worth. Match the tenure to how long the thing you bought will last.
Tenure vs EMI: the real tradeoff
Every extra year cuts the EMI and adds interest. Here is the exchange rate, on a ₹30L home loan at 8.5%.
Each row below is the same loan, the same rate, the same borrower. Only the number of months changes. The last column is what the extra year buys you in monthly cash flow, and what it costs in total.
| Tenure | Monthly EMI | Total interest | Total payment | Extra interest vs 15 years |
|---|---|---|---|---|
| 15 years | ₹29,542 | ₹23,17,594 | ₹53,17,594 | — |
| 20 years | ₹26,035 | ₹32,48,327 | ₹62,48,327 | +₹9,30,733 |
| 25 years | ₹24,157 | ₹42,47,044 | ₹72,47,044 | +₹19,29,450 |
| 30 years | ₹23,067 | ₹53,04,266 | ₹83,04,266 | +₹29,86,672 |
Total interest by tenure — ₹30L at 8.5%
Going from 15 to 30 years buys ₹6,475 a month and costs ₹29,86,672. That is 461 months of the saving: you would need to stay on the lower EMI for 38 years just to break even on the interest. A 30-year tenure only makes sense when the 15-year EMI is genuinely unaffordable, not when it is merely uncomfortable.
What 0.5% actually costs
The rate is the price per year. This is what it looks like when you move it half a point at a time, on the same ₹30L / 20-year loan.
| Rate | Monthly EMI | Total interest | Difference vs 8.5% |
|---|---|---|---|
| 8.0% | ₹25,093 | ₹30,22,368 | −₹2,25,959 |
| 8.5% | ₹26,035 | ₹32,48,327 | — |
| 9.0% | ₹26,992 | ₹34,78,027 | +₹2,29,700 |
| 9.5% | ₹27,964 | ₹37,11,345 | +₹4,63,018 |
| 10.0% | ₹28,951 | ₹39,48,156 | +₹6,99,829 |
Read the last column against the rate column: each 0.5% step costs about ₹2.3 lakh over 20 years. A 1.5% gap — entirely normal between the best and worst offer a borrower is shown on the same day — costs ₹6,99,829. That is more than a year of EMIs.
The 0.25% question, answered
Lenders rarely move in half points. They move in quarter points, and quarter points get dismissed as noise. On a ₹50L / 20-year loan, going from 8.50% to 8.25% cuts the EMI from ₹43,391 to ₹42,603 and the total interest by ₹1,89,091.
| Same ₹50L / 20 years | EMI | Total interest | Difference |
|---|---|---|---|
| 8.25% | ₹42,603 | ₹52,24,788 | −₹1,89,091 |
| 8.50% (benchmark) | ₹43,391 | ₹54,13,879 | — |
| 8.75% | ₹44,186 | ₹56,04,529 | +₹1,90,650 |
| 9.00% | ₹44,986 | ₹57,96,711 | +₹3,82,832 |
A 0.25% cut is worth about ₹1.89 lakh on ₹50L over 20 years. If the lender wants a 0.5% fee plus GST (₹29,500) to grant it, the cut is still worth taking — but if they want 1% plus GST (₹59,000) for the same 0.25%, you are paying a third of the benefit upfront for a gain that only arrives if you keep the loan for two decades. Ask for the fee and the rate in the same email, and compute both.
What actually moves your offered rate, in rough order of effect: credit score (the single biggest bucket), loan-to-value (a 20% down payment buys a better rate than 10%), employer category for salaried borrowers, and existing relationship (salary account, deposits). A rate that is 0.25% lower is worth roughly ₹1.9 lakh on a ₹50L loan — more than most people save by shopping for a year on everything else in their budget.
EMI in Excel and Google Sheets
Six functions cover every loan question — and one of them will tell you whether the rate you were quoted is the rate you are paying.
Everything in this guide reduces to one spreadsheet function. Excel and Google Sheets use identical names and arguments, so anything below works in both. The only difference you may hit is the separator: comma in English locales, semicolon in many European ones.
| Function | What it answers | Use it like this |
|---|---|---|
| PMT | The EMI | =−PMT(8.5%/12, 240, 3000000) |
| IPMT | Interest inside one EMI | =−IPMT(8.5%/12, 1, 240, 3000000) |
| PPMT | Principal inside one EMI | =−PPMT(8.5%/12, 1, 240, 3000000) |
| NPER | How long a given EMI takes | =NPER(8.5%/12, −26035, 3000000) |
| RATE | The rate implied by an EMI you were quoted | =RATE(240, −26035, 3000000)*12 |
| CUMIPMT | Total interest between two months | =−CUMIPMT(8.5%/12, 240, 3000000, 1, 12, 0) |
The minus sign in front is not a typo. Excel treats money going out as negative, so PMT returns −26,035. Wrap it in ABS() or put a minus in front if you want the positive number the bank quotes.
Build the four-cell version first
- B1 = 3000000 (loan)
- B2 = 8.5% (annual rate)
- B3 = 240 (months)
- B4 =
=−PMT(B2/12,B3,B1)→ 26,035 - B5 =
=B4*B3−B1→ 32,48,327 total interest
If B4 does not match the calculator to the rupee, one of the three inputs is wrong — usually the tenure, entered in years instead of months.
Expand it into a schedule
- A7 = 1, B7 =
=$B$4, C7 ==ROUND($B$1*$B$2/12,0) - D7 =
=B7−C7(principal), E7 ==$B$1−D7(balance) - A8 =
=A7+1, C8 ==ROUND(E7*$B$2/12,0), E8 ==E7−(B8−C8) - Fill A8:E8 down to row 246 (240 payments plus the header).
The last row should land at a balance of zero or within a few rupees of it. If it goes negative, your EMI is rounded up; if it stops short, it is rounded down. Both are normal, and both are why bank schedules differ from a pure formula by a rupee or two.
Audit the sanction letter
- Take the EMI printed in your sanction letter, e.g. ₹26,035 for ₹30L over 240 months.
- Run
=RATE(240,−26035,3000000)*12. It returns 8.50%. - Now run it with the EMI actually debited from your account, if it differs.
- If the result is higher than the quoted rate, the gap is fees, insurance or a rate reset — not rounding.
This one formula settles most disputes with a lender faster than any phone call, because it converts everything they charge you into the single number you can compare.
=CUMIPMT(8.5%/12,240,3000000,1,12,0) returns the interest paid in the first 12 months: ₹2,52,709. You will have paid ₹3,12,416 and reduced the loan by only ₹59,707. Run the same function for months 229–240 and the split reverses. That single comparison explains why prepaying early is worth so much more than prepaying late.
Amortization: where the crossover is
A month-by-month split of one real loan, measured — not estimated.
An amortization schedule lists every payment, split into interest and principal, with the balance after each one. Every row is arithmetic: interest = opening balance × monthly rate; principal = EMI − interest; new balance = old balance − principal.
Here is one schedule at six points, for ₹30,00,000 at 8.5% over 20 years (EMI ₹26,035):
| Month | Interest in that EMI | Principal in that EMI | Balance after |
|---|---|---|---|
| 1 | ₹21,250 | ₹4,785 | ₹29,95,215 |
| 12 | ₹20,864 | ₹5,171 | ₹29,40,293 |
| 61 | ₹18,727 | ₹7,308 | ₹26,36,508 |
| 121 | ₹14,874 | ₹11,161 | ₹20,88,654 |
| 143 | ₹12,999 | ₹13,036 | ₹18,22,082 |
| 181 | ₹8,988 | ₹17,046 | ₹12,51,916 |
| 240 | ₹183 | ₹25,852 | ₹0 |
After 10 years you have paid ₹31.24 lakh and still owe ₹20.99 lakh — 70% of the original loan. And month 143 is the first month in which principal (₹13,036) finally beats interest (₹12,999): that is 11 years and 11 months into a 20-year loan. The “crossover in 3–4 years” advice is a 5-year-car-loan fact repeated for 20-year home loans, and it is wrong by roughly a decade.
The crossover depends on tenure, not on the rate. On a 5-year ₹5L loan at 10%, principal beats interest in month 1. Shorten a 20-year home loan to 15 years and the crossover arrives earlier too, because every EMI carries a larger principal share from the start. If a lender or a blog tells you a fixed month without telling you the tenure, the number means nothing.
Prepayment math, corrected
A prepayment gives you a choice the lender will not volunteer: shrink the tenure, or shrink the EMI. The gap between the two is about four to one.
Any extra rupee paid against principal stops earning interest from that month onward. What happens next is a choice, and most borrowers are never told it is one. On a ₹30L / 9% / 20-year loan (EMI ₹26,992, total interest ₹34,78,027), paying ₹1,00,000 in month 1 produces two very different outcomes:
Keep the EMI, cut the tenure
You save ₹4,53,921 in interest and the loan closes 20 months earlier. Your monthly outgo does not change at all — you simply stop paying sooner.
Cut the EMI, keep the tenure
Your EMI falls from ₹26,992 to ₹26,092 (₹900 a month) and you save ₹1,15,934 in interest. Same end date, smaller payments, a quarter of the saving.
Neither is wrong. Cutting the EMI is what you do when cash flow is the problem; cutting the tenure is what you do when cash flow is fine and you want the debt gone. The point is that the lender defaults to whichever is easier for them, so you have to ask.
Timing matters more than size
The same rupee is worth more in month 1 than in month 120, because in month 120 most of the remaining interest has already been paid. Both columns below are the same loan; only the month of the prepayment changes.
| Extra payment | Paid in | Keep EMI: interest saved | Keep EMI: months cut | Cut EMI instead: interest saved |
|---|---|---|---|---|
| ₹10,000 | Month 1 | ₹49,361 | 2 | ₹11,593 |
| ₹10,000 | Month 12 | ₹44,724 | 2 | ₹10,962 |
| ₹10,000 | Month 60 | ₹28,296 | 1 | ₹8,310 |
| ₹10,000 | Month 120 | ₹14,514 | 0 | ₹5,250 |
| ₹1,00,000 | Month 1 | ₹4,53,921 | 20 | ₹1,15,934 |
| ₹1,00,000 | Month 12 | ₹4,13,193 | 19 | ₹1,09,622 |
| ₹1,00,000 | Month 60 | ₹2,66,028 | 13 | ₹83,102 |
| ₹1,00,000 | Month 120 | ₹1,38,021 | 8 | ₹52,496 |
A cut of 0 months means the loan still ends in month 240, but the final instalment is smaller — that is where the ₹14,514 comes from. Prepayment saves interest in direct proportion to how much of the loan's life is still ahead.
Prepaying without choosing the mode. If you hand over ₹1,00,000 and say nothing, the default is usually an EMI reduction — ₹1.16 lakh of savings instead of ₹4.54 lakh. State it in writing on the prepayment request: “reduce tenure, keep EMI unchanged”. Then check the next statement, because the instruction is applied by a person.
What the 2026 rule actually says
The RBI’s (Pre-payment Charges on Loans) Directions, 2025 (2 July 2025, effective 1 January 2026) removed prepayment and foreclosure charges on floating-rate loans to individuals for purposes other than business. In practice, for a home, car, education or personal loan on a floating rate, that means:
- No charge on partial prepayment or full foreclosure, regardless of when you do it.
- No lock-in required before you are allowed to prepay.
- Applies whether the money comes from your savings or from a balance transfer to another lender.
- Fixed-rate loans are not covered — a fixed-rate home loan can still carry a charge, per its contract.
- Business and non-individual loans are outside this protection.
If a 2026 sanction letter quotes a foreclosure penalty on a floating-rate home loan to you as an individual, that clause does not sit with the Directions. Ask for it to be struck before you sign rather than arguing about it after you try to prepay.
Prepay or invest — after tax
The comparison is not 8.5% against 12%. It is your post-tax loan cost against your post-tax return, and both numbers move once tax is applied.
Prepaying a loan earns a guaranteed return equal to the rate you no longer pay. Investing earns an uncertain return. To compare them honestly, both have to be converted to the same basis: what you keep after tax.
| Where the rupee goes | Headline rate | After tax, 30% slab | How the tax works |
|---|---|---|---|
| Personal or car loan | 14.0% | 14.00% | No deduction on interest for a personal loan |
| Home loan interest above the 24(b) cap | 8.5% | 8.50% | Only ₹2L of interest is deductible per year |
| Education loan (Section 80E) | 10.0% | 7.00% | Full interest deductible, no cap, 8 years |
| Home loan within the 24(b) cap | 8.5% | 5.95% | Interest × (1 − slab) |
| Equity funds, 10-year hold | 12.0% | 11.01% | 12.5% LTCG on gains above ₹1.25L |
| PPF | 7.1% | 7.10% | Entirely tax-free |
| FD or debt fund | 7.0% | 4.90% | Taxed at your slab rate |
Clear the personal loan first (14% guaranteed saving beats any plausible post-tax return). Then the home-loan interest above the ₹2L cap (8.50%). Then the education loan (7.00%). The last rupee to prepay is the home-loan slice that is already deductible at 5.95% — and even then only if you would genuinely invest the money rather than spend it.
Why the cap matters more than the headline rate
On a ₹50L / 8.5% / 20-year loan, year-1 interest is ₹4,21,182 — more than twice the ₹2L deduction limit. Only ₹2L of it is deductible, so the blended post-tax cost of that year is 7.29%, not 5.95%. As the loan amortizes, annual interest falls; the year it drops below ₹2L, the whole interest becomes deductible and the effective cost of those rupees falls to 5.95%.
This is the opposite of what most prepayment advice assumes. The early years are when your home loan is at its most expensive after tax AND when a prepayment saves the most interest. Both effects point the same way, which is why a lump sum in year 2 or 3 is worth far more than the same lump sum in year 15.
Three checks before you send the money
Is the emergency fund intact?
Six months of expenses in a liquid form comes before any prepayment. A loan you can service is not a crisis; a loan you cannot service because your savings went into principal is.
Are you on the old regime?
Sections 24(b) and 80C exist only in the old regime. On the new regime the home loan has no deduction at all, so its post-tax cost is the full 8.5% — which moves it above the education loan in the order above, and makes prepaying it more attractive than most calculators suggest.
Would you actually invest it?
The 11.01% equity figure assumes the money is invested for a decade and left alone. If the realistic alternative is a savings account at 3%, the loan wins by a wide margin regardless of the table. Compare against your behaviour, not against the best available product.
How much loan you can actually carry
Two separate ceilings apply — one from your income, one from the property value. Whichever is lower decides your loan.
Banks express the income limit as FOIR (fixed obligation to income ratio): all your EMIs together, divided by take-home pay. Most lenders cap it at 40–55%, and existing obligations count first. If you already pay a ₹8,000 car EMI, that ₹8,000 is gone before the home loan is assessed.
| Take-home pay | Max total EMI at 40% | Loan at 9% / 20y | Comfortable EMI at 30% | Loan at 30% |
|---|---|---|---|---|
| ₹50,000 | ₹20,000 | ₹22.2L | ₹15,000 | ₹16.7L |
| ₹75,000 | ₹30,000 | ₹33.3L | ₹22,500 | ₹25.0L |
| ₹1,00,000 | ₹40,000 | ₹44.5L | ₹30,000 | ₹33.3L |
| ₹1,50,000 | ₹60,000 | ₹66.7L | ₹45,000 | ₹50.0L |
| ₹2,00,000 | ₹80,000 | ₹88.9L | ₹60,000 | ₹66.7L |
The 30% column is the one worth using, not the 40% column. At 40% of take-home, a single unexpected month — a medical bill, a repair, a gap between jobs — turns into a missed EMI. At 30% there is room to absorb it.
The second ceiling nobody mentions first
Loan-to-value (LTV) caps how much of the property a bank will finance, regardless of your income: up to 90% for loans of ₹30L or less, up to 80% between ₹30L and ₹75L, and up to 75% above ₹75L. Stamp duty and registration — typically 5–8% of the property value — are never financed and always come from your own funds.
| Scenario | Income ceiling | LTV ceiling | Loan you get |
|---|---|---|---|
| ₹60L flat, ₹1L take-home | ₹44.5L | ₹48.0L (80%) | ₹44.5L — income binds |
| ₹40L flat, ₹1L take-home | ₹44.5L | ₹32.0L (80%) | ₹32.0L — LTV binds |
| ₹1.2Cr flat, ₹2L take-home | ₹88.9L | ₹90.0L (75%) | ₹88.9L — income binds |
In the second row the borrower can afford the EMI on a ₹44.5L loan but can only borrow ₹32L, so the gap of ₹8L plus stamp duty has to come from savings. That is the real reason people with comfortable salaries still cannot buy the flat they had in mind — and it is worth knowing before you start shortlisting.
An in-principle sanction of ₹44.5L is a statement about the bank’s comfort, not yours. It does not account for school fees, parents’ support, or the fact that your salary may not rise at the rate your EMI is fixed. Run the number at 30% of take-home and treat anything above it as a decision you have to justify, not a limit you are entitled to.
Tax on home and education loans
The deductions are real, but they are worth exactly your slab rate — and only in the old regime. Here is what each one is actually worth.
| Section | Covers | Cap | Conditions that trip people up |
|---|---|---|---|
| 24(b) | Home loan interest | ₹2,00,000 per year | Self-occupied or let out. For a let-out property the interest is capped at ₹2L per year (post AY 2020-21), and the resulting loss can be set off against other income only up to ₹2L. |
| 80C | Principal repayment, stamp duty, registration | ₹1,50,000 per year | Shares the ₹1.5L cap with EPF, PPF, ELSS and life insurance. Withdrawn if you sell within 5 years of possession. |
| 80E | Education loan interest | No cap | Interest only, never principal. Available for 8 consecutive years from the year repayment starts. Not allowed in the new regime. |
| 80EEA | Extra affordable-housing interest | ₹1,50,000 per year | Closed. Only for loans sanctioned April 2019 to March 2022, property up to ₹45L, first-time buyer. |
Now the arithmetic that matters. A ₹50L / 8.5% / 20-year loan pays ₹4,21,182 of interest in year 1. Only ₹2,00,000 of that is deductible, and at the 30% slab plus 4% cess (31.2% effective) it is worth ₹62,400 — not ₹1,05,000.
| Your slab | 24(b) on ₹2L | 80C on ₹1.5L | Combined, per year |
|---|---|---|---|
| 5% (+cess) | ₹10,400 | ₹7,800 | ₹18,200 |
| 20% (+cess) | ₹41,600 | ₹31,200 | ₹72,800 |
| 30% (+cess) | ₹62,400 | ₹46,800 | ₹1,09,200 |
Two conclusions follow. First, the benefit scales with income: the same loan is worth six times more to a 30% taxpayer than to a 5% taxpayer. Second, it is largest in the early years, when interest is highest — year 1 here is ₹4.21L of interest, of which only ₹2L is claimable, so the deduction covers less than half of what you actually pay.
The old regime gives you 24(b) + 80C; the new regime gives lower slab rates but neither deduction. For a ₹1L-per-month salaried borrower with a home loan, the two can land close enough that the only way to know is to compute both with your actual numbers. Do not assume the deduction wins — and do not assume the new regime wins either.
One more thing that is not a deduction but is worth as much: interest paid during the pre-construction period (the pre-EMI in section 16) is deductible under 24(b) in five equal instalments starting from the year of possession — not in the year you paid it. Keep the interest certificates.
6 mistakes and what each costs
Every number below is the difference between doing it the common way and doing it the correct way, on a loan you could realistically take.
| Mistake | What it costs | Do this instead |
|---|---|---|
| 1. Comparing EMIs instead of totals | ₹6,475 a month cheaper, ₹20,55,939 more expensive (₹30L at 8.5%, 30 years vs 20) | Compare EMI × months. The lower EMI is almost always the longer loan, and the longer loan almost always costs more. |
| 2. Treating the quoted rate as the cost | A 0.5% processing fee plus GST is ₹29,500 on ₹50L and turns 8.50% into 8.58% | Ask for the APR, which the lender must compute including fees. Compare APR to APR, never rate to rate. |
| 3. Prepaying without naming the mode | ₹3,37,987 of interest not saved on a ₹1L prepayment in month 1 (₹1,15,934 instead of ₹4,53,921) | Write “reduce tenure, keep EMI unchanged” on the request, then verify it on the next statement. |
| 4. Ignoring the reset clause | A 1% rate rise absorbed as a tenure extension adds ₹16,91,860 and 39 months to a ₹50L loan | Ask the lender to apply resets to the EMI, not the tenure, and confirm it in the sanction letter. |
| 5. Dismissing small prepayments | ₹10,000 in month 1 is worth ₹49,361 — not the ₹5,400 that gets repeated online | Prepay whatever is spare, early. There is no minimum that makes it pointless. |
| 6. Reading a flat rate as a reducing rate | A “10%” flat car loan costs the same as 17.3% reducing over 5 years | Ask “flat or reducing?” before you compare. If flat, convert before you decide. |
Five of the six are not arithmetic errors — they are presentation choices made by the lender, repeated by the borrower. The EMI is shown, the total is not. The rate is quoted, the APR is not. The reset is described, the cost is not. The single most useful habit in this guide is asking for the second number every time someone shows you the first.
The rate-reset trap
A floating rate does not just change your EMI. It gives the lender a choice — and that choice can cost four times as much as the rate rise itself.
Fixed means one rate for the whole tenure, usually priced 0.5–1% above the floating rate at the start. Floating means the rate follows a benchmark, and the loan is re-priced whenever the benchmark moves. The part almost nobody reads is the reset clause: when the rate goes up, does the lender raise the EMI, extend the tenure, or ask you which you prefer?
Take a ₹50L / 8.5% / 20-year loan (EMI ₹43,391). After 36 EMIs the balance is ₹46,74,300 and the remaining interest, if nothing changes, is ₹41,77,497. Now the rate resets:
| Rate reset | New EMI | EMI increase | Cost if absorbed by EMI | Cost if absorbed by tenure |
|---|---|---|---|---|
| +0.5% (to 9.0%) | ₹44,817 | +₹1,426 | +₹2,90,947 | +₹7,29,566 · 16.8 months longer |
| +1.0% (to 9.5%) | ₹46,265 | +₹2,874 | +₹5,86,328 | +₹16,91,860 · 39 months longer |
| +1.5% (to 10.0%) | ₹47,734 | +₹4,343 | +₹8,86,030 | +₹30,68,919 · 70.7 months longer |
A 1% reset costs ₹5,86,328 as a higher EMI, or ₹16,91,860 as a longer tenure — 2.9 times more. The tenure route feels gentler because the monthly number does not move, but the loan now runs to month 279 instead of 240, ending 3 years and 3 months later. If nobody tells you there was a choice, this is where the money goes.
RBI’s circular of 18 August 2023 (DOR.MCS.REC.32/01.01.003/2023-24, effective 1 January 2024) requires lenders to give borrowers the option of a higher EMI or a longer tenure when a floating rate resets, and to communicate the change in writing. Whether your lender applies it to a home loan or reads it narrowly, the practical point is the same: the choice is the borrower's to make, and it has to be asked for.
Is the fixed rate worth the premium?
A fixed rate at 9.0% instead of a floating 8.5% costs ₹1,595 more every month from day one — ₹3,82,832 more over 20 years if the floating rate never moves. The floating borrower only loses that much if the average rate over the whole tenure exceeds roughly 9%. Historically, floating has been cheaper over long horizons in India, but that is a statement about the past, and the reason to pick fixed is not the average — it is the inability to absorb the reset. If a ₹2,874 increase would break your budget, pay for the certainty.
“On a benchmark change, the borrower may choose between EMI revision and tenure extension.” And: “The lender will notify the borrower in writing within 30 days of the reset, stating the new rate, the new EMI and the revised residual tenor.” Both are reasonable requests, and both are much easier to agree before disbursal than after.
Pre-EMI during construction
If you buy under construction, you pay interest on money you have borrowed but cannot use — before the loan has even started.
A home loan is disbursed in tranches as the builder completes stages. Until the last tranche goes out, the lender charges pre-EMI: interest only, on whatever has been released, with no principal component. The full EMI starts only after full disbursal. On a ₹50L loan at 8.5% over a 24-month construction period, with 25% released every six months:
| Months | Amount disbursed | Pre-EMI per month | Paid in that block |
|---|---|---|---|
| 1–6 | ₹12,50,000 | ₹8,854 | ₹53,125 |
| 7–12 | ₹25,00,000 | ₹17,708 | ₹1,06,250 |
| 13–18 | ₹37,50,000 | ₹26,563 | ₹1,59,375 |
| 19–24 | ₹50,00,000 | ₹35,417 | ₹2,12,500 |
| Total pre-EMI, 24 months | ₹5,31,250 | ||
From month 25 the EMI is ₹43,391 for 240 months. Total repaid: ₹1,09,45,129. The identical loan on a ready-to-move property repays ₹1,04,13,879. The difference, ₹5,31,250, is the price of the construction period — and it buys you nothing, because the principal has not moved at all. Every rupee of that ₹5.3 lakh was interest on a balance that stayed exactly where it started.
Under-construction property also attracts 5% GST on the agreement value (1% for affordable housing) where a ready-to-move unit attracts none — on a ₹60L flat that is ₹3,00,000. And if your rent continues during construction, add 24 months of rent to the true cost. A ₹60L under-construction flat can easily cost ₹8–10 lakh more than the same flat bought ready, before the price difference is considered.
Two practical notes. First, ask for the disbursement schedule in writing before you sign — if the builder claims 40% completion in month 6, that is when your pre-EMI jumps. Second, if the builder offers to pay the pre-EMI for you (a subvention scheme), the cost is already inside the price; compare the all-in price against a ready property rather than comparing the payment schedules, because the schedule is the part designed to look good.
Reference grid: EMI per ₹1 lakh
Six rates and six tenures, quoted per ₹1 lakh borrowed. Multiply by your loan size in lakhs.
| Rate | 5 years | 10 years | 15 years | 20 years | 25 years | 30 years |
|---|---|---|---|---|---|---|
| 8.0% | ₹2,028 | ₹1,213 | ₹956 | ₹836 | ₹772 | ₹734 |
| 9.0% | ₹2,076 | ₹1,267 | ₹1,014 | ₹900 | ₹839 | ₹805 |
| 10.0% | ₹2,125 | ₹1,322 | ₹1,075 | ₹965 | ₹909 | ₹878 |
| 11.0% | ₹2,174 | ₹1,378 | ₹1,137 | ₹1,032 | ₹980 | ₹952 |
| 12.0% | ₹2,224 | ₹1,435 | ₹1,200 | ₹1,101 | ₹1,053 | ₹1,029 |
| 14.0% | ₹2,327 | ₹1,553 | ₹1,332 | ₹1,244 | ₹1,204 | ₹1,185 |
How to use it: find the row for your rate, the column for your tenure, then multiply by the loan in lakhs. A ₹30L loan at 9% for 20 years: 30 × ₹900 = ₹27,000 (the exact figure is ₹26,992). A ₹75L loan at 8% for 30 years: 75 × ₹734 = ₹55,050.
Two patterns hold at every loan size. Doubling the tenure cuts the EMI by about a third, never by half — at 9%, ₹1 lakh costs ₹1,267 over 10 years and ₹900 over 20, a 29% fall. And every 2 percentage points of rate adds roughly 14% to the EMI at 20 years, which is why a “small” rate difference is never small.
For a 20-year loan at 9%, every ₹1 lakh borrowed costs ₹900 a month — close enough to ₹1,000 that the rough version is useful for sanity checks. But the same ₹1 lakh at 14% over 5 years costs ₹2,327, and at 8% over 30 years only ₹734. A single rule of thumb cannot cover a 3× spread, which is why the grid exists.
Using the AFFLIGO calculator
Two screens: the inputs that matter, and the output worth reading.
Set the three inputs
The loan amount runs from ₹10,000 to ₹1,00,00,000; the rate from 0% to 30% in 0.1% steps; the tenure from 1 to 30 years, or the same span in months via the toggle. Type an exact figure into the number box instead of dragging when precision matters — a sanction letter quotes exact values, and a slider snaps to the nearest step.
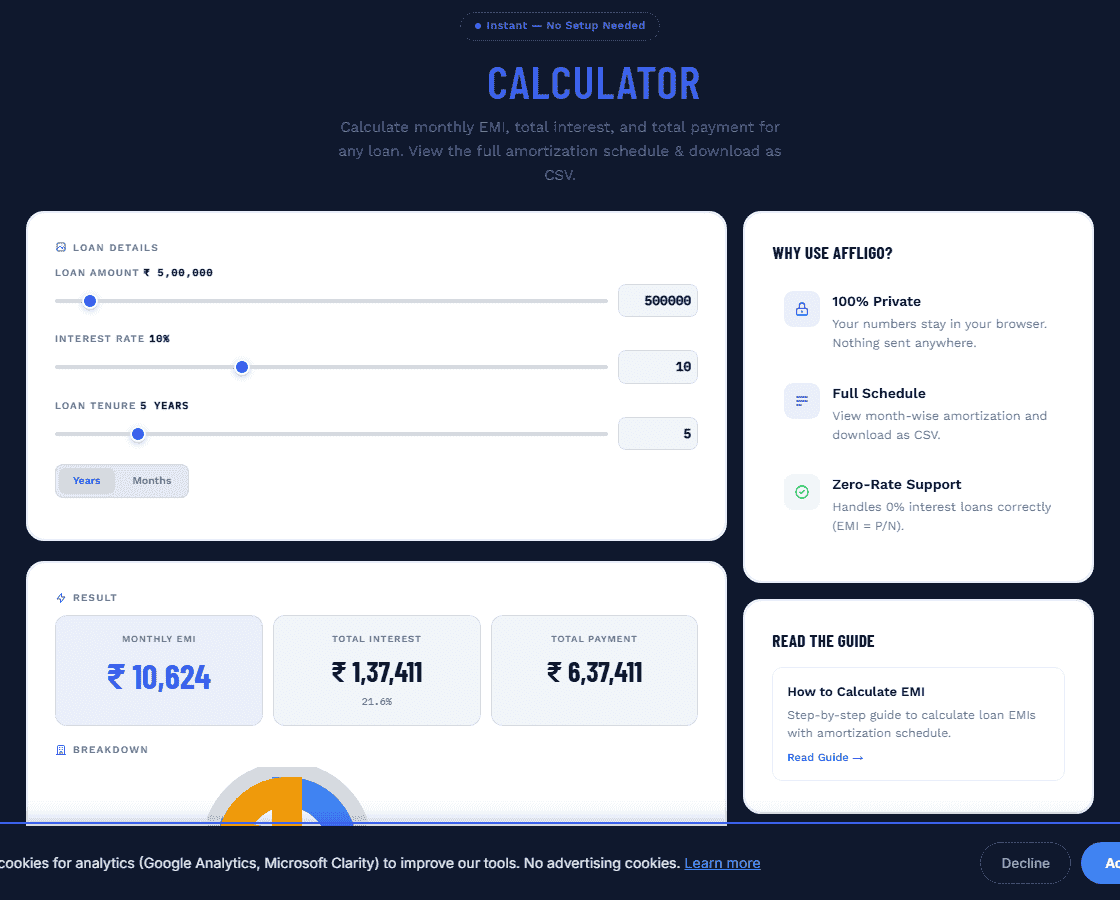
Read four outputs, then the schedule
Results update as you type: monthly EMI, total interest, total payment and interest as a share of the total. The pie chart shows the principal-to-interest split visually. Expand the amortization table for every month, or download it as CSV — the file carries the same four columns as section 8, so it opens straight into the spreadsheet audit.
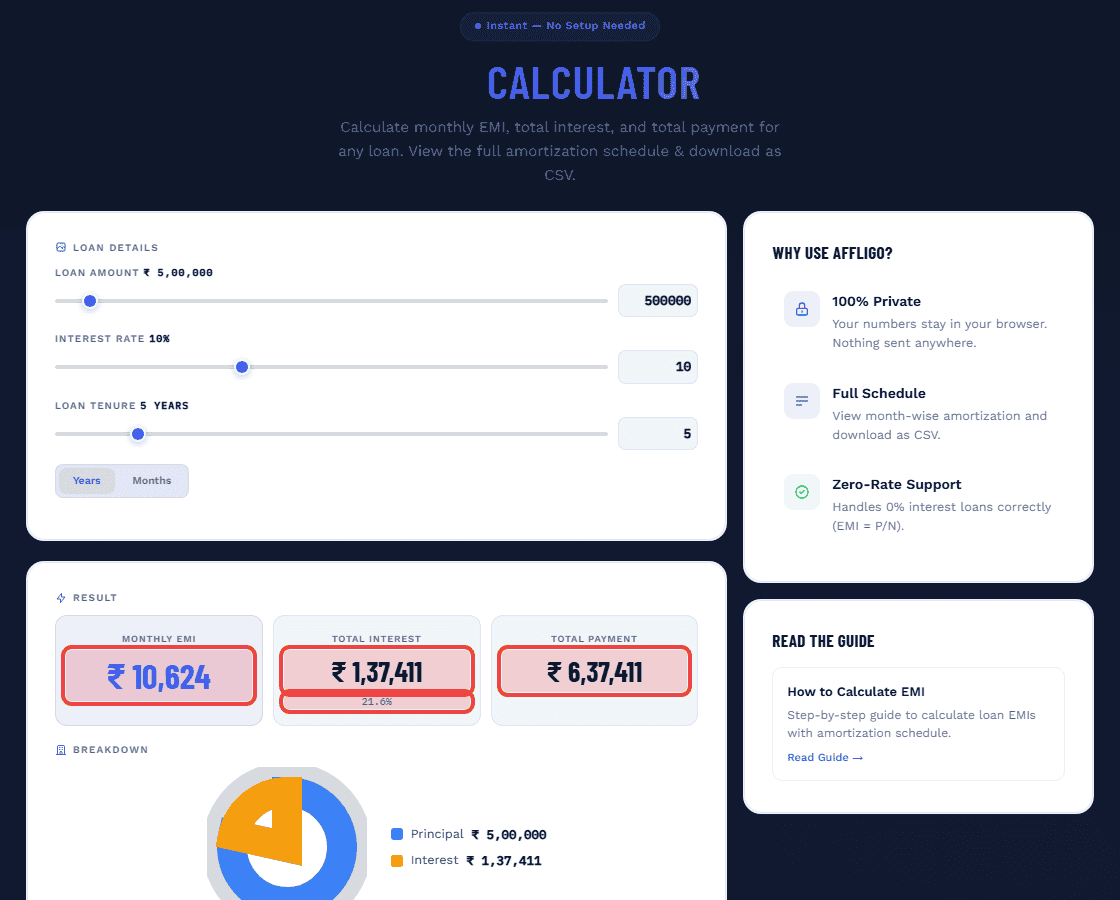
It solves the annuity formula, nothing more. It has no prepayment simulation, no fee field, no reset modelling and no tax adjustment. Section 10 gives the prepayment numbers, section 4 the fees, section 15 the reset cost, section 13 the tax. The tool answers “what is my EMI”; those sections answer “what will this loan actually cost me”.
Two sanity checks before you rely on any output: confirm the tenure unit (years vs months) and confirm whether the rate you entered is the annual rate, not the monthly one. Those two mistakes account for almost every “the calculator is wrong” report.
How these numbers were verified
Every figure in this guide was produced by an independent calculation and cross-checked against the calculator. Where an earlier version of this page was wrong, the old value is listed.
The method is deliberately narrow, because a loan has no ambiguity. For each case I computed the reducing-balance EMI in two independent ways — the closed-form formula and a month-by-month amortization loop — then compared both against the live calculator output to the rupee. Prepayment and reset figures come from re-running the schedule with the balance adjusted at the stated month; the grid in section 17 comes from the same formula at six rates and six tenures.
| Claim | Earlier version of this page | Verified value |
|---|---|---|
| ₹10,000 prepaid in month 1, ₹30L / 9% / 20y | saves ₹5,400 | ₹49,361 |
| The same ₹10,000 prepaid in month 50 | saves ₹600 | ₹31,251 |
| ₹1,00,000 prepaid, tenure reduced | saves ₹3,30,000 | ₹4,53,921 |
| ₹1,00,000 prepaid, EMI reduced | saves ₹1,80,000 | ₹1,15,934 |
| EMI on ₹30L / 8.5% / 15y | ₹29,957 · ₹23,92,260 interest | ₹29,542 · ₹23,17,594 |
| EMI on ₹30L / 8.5% / 25y | ₹24,039 · ₹42,11,700 interest | ₹24,157 · ₹42,47,044 |
| ₹10L at 10% for 20 years, total cost | 2.8× principal (Rule of 72) | 2.32× |
| Crossover month, ₹5L / 10% / 5y | month 35 | month 1 |
| Calculator loan range | ₹10,000 to ₹10 crore | ₹10,000 to ₹1 crore |
| Prepayment simulation feature | listed as available | not a feature of the tool |
The rate figures in the examples are illustrative, not live quotes, because live quotes go stale within a quarter and a guide that quotes them is wrong by the time you read it. What does not go stale is the arithmetic: the difference between 8.5% and 9.5% will always be about ₹2.3 lakh per ₹30L over 20 years. Where a rule is cited, it is cited by name and date so you can check the source: the RBI’s reset circular of 18 August 2023, and the (Pre-payment Charges on Loans) Directions, 2025 effective 1 January 2026.
If you find a number here that does not reproduce from the formula, that is a defect and worth reporting — the figures above are meant to be checkable, not authoritative. The two largest errors in the previous version were the prepayment savings (understated by a factor of nine) and a crossover month borrowed from a 5-year car loan. Both are now computed from a schedule rather than repeated from secondary sources.
Frequently asked questions
Sixteen answers that match the arithmetic above.
EMI is the fixed monthly payment that clears a loan over its tenure, combining interest on the outstanding balance and repayment of principal. It is calculated with the reducing-balance formula EMI = P × r × (1+r)n ÷ ((1+r)n − 1), where r is the annual rate ÷ 12 ÷ 100 and n is the number of months. ₹30,00,000 at 8.5% for 20 years gives ₹26,035 a month and ₹32,48,327 of total interest.
No — a flat rate is always more expensive at the same quoted number, because interest is charged on the original amount for the whole tenure instead of on the falling balance. A “10%” flat loan over 5 years costs the same as a 17.3% reducing-balance loan, and on ₹5,00,000 that is ₹1,12,589 more interest. Ask “flat or reducing?” before comparing two quotes.
It reduces the EMI and increases the total cost, every time. On ₹30,00,000 at 8.5%, going from 15 years to 30 years cuts the EMI from ₹29,542 to ₹23,067 but adds ₹29,86,672 of interest — you would need to keep the lower EMI for 38 years to break even on that trade. Choose the shortest tenure whose EMI you can actually service.
About ₹2.3 lakh per ₹30 lakh over 20 years: ₹30,00,000 at 9.0% costs ₹34,78,027 in interest against ₹32,48,327 at 8.5%. Even a quarter point is not noise — 8.50% to 8.25% on ₹50 lakh saves ₹1,89,091. Always convert a rate offer into total interest before judging it.
Prepayment reduces the principal, so every future month charges interest on a smaller balance. You then choose the mode: keeping the EMI and cutting the tenure saves far more than cutting the EMI and keeping the tenure. On ₹30,00,000 at 9% for 20 years, ₹1,00,000 in month 1 saves ₹4,53,921 if you keep the EMI, or ₹1,15,934 if you reduce it — a difference of ₹3,37,987 from one instruction.
Not on a floating-rate loan to an individual for non-business use. The RBI’s (Pre-payment Charges on Loans) Directions, 2025, effective 1 January 2026, removed prepayment and foreclosure charges in that case, with no lock-in. Fixed-rate loans are outside that protection and can still carry a charge, so check the clause in your own agreement.
Pre-EMI is interest-only payment during construction, charged on the amount disbursed so far. It reduces no principal at all, so it is pure additional cost. On ₹50,00,000 at 8.5% over a 24-month construction period, pre-EMI totals about ₹5,31,250 — the same loan on a ready property repays that much less over its life.
The loan is re-priced and the lender either raises the EMI or extends the tenure — and RBI’s circular of 18 August 2023 requires that you be offered the choice. The gap between the two is large: a 1% rise on ₹50,00,000 with 204 months left costs ₹5,86,328 as a higher EMI, but ₹16,91,860 as a longer tenure. Ask for the EMI route, and ask for the new residual tenor in writing.
Choose fixed if a reset would break your budget; choose floating if you can absorb one and want the lower starting rate. A fixed rate typically costs 0.5–1% more, which is ₹1,595 a month on ₹50,00,000 at 9.0% versus 8.5% — ₹3,82,832 more over 20 years. That premium buys certainty, not a cheaper loan.
Roughly ₹44.5 lakh on ₹1,00,000 take-home at 9% over 20 years if the bank allows a 40% FOIR, or ₹33.3 lakh at a comfortable 30%. ₹50,000 supports about ₹22.2 lakh at 40%. A second ceiling applies too: loan-to-value caps borrowing at 90% of the property up to ₹30 lakh, 80% up to ₹75 lakh, and 75% above that, and stamp duty is never financed.
Use =−PMT(rate/12, months, loan). For ₹30,00,000 at 8.5% over 240 months, =−PMT(8.5%/12,240,3000000) returns 26,035. To audit a quote you were given, run it backwards: =RATE(240,−26035,3000000)*12 returns 8.50%, so any gap between that and the quoted rate is fees, insurance or a reset.
At the 30% slab plus 4% cess, Section 24(b) on the ₹2,00,000 cap is worth ₹62,400 a year, and Section 80C on ₹1,50,000 is worth ₹46,800 — ₹1,09,200 combined, not the ₹1.05 lakh that the 24(b) cap alone is often said to produce. Both are available only in the old regime, and only on interest actually paid, so the benefit shrinks as the loan amortizes.
Six common reasons, in order of size: the tenure was entered in years instead of months, insurance or a fees-only loan was bundled into the principal, the rate was reset since the quote, the lender computes interest daily rather than monthly, the EMI is rounded up to the nearest rupee, or a moratorium changed the start date. Any gap beyond a rupee or two is worth asking about in writing.
Compare post-tax numbers, not headline rates. A personal loan at 14% costs 14% after tax and beats any realistic investment return; a home loan whose interest is deductible at the 30% slab costs 5.95% after tax, which is below an 11.01% post-tax equity return over ten years. Prepay in order of post-tax cost, and only after your emergency fund is funded.
A late fee and penal interest are charged, a bounced auto-debit adds a separate charge, and the missed payment is reported to the credit bureaus — usually within 30 days. An account becomes an NPA when it is overdue for more than 90 days, not after a fixed count of missed EMIs. Call the lender before the due date rather than after; most will restructure a single instalment without reporting it.
750 and above gets the best published rates at most lenders, with 800+ giving the most negotiating room. A score in the 700–750 band typically attracts 0.25–0.5% more, which on ₹50 lakh over 20 years is ₹1.9–3.8 lakh. Below 700, expect higher pricing, a lower loan-to-value, or a co-applicant requirement. Check the report itself, not just the score — a settled or wrongly reported account can be corrected.
Key Takeaways
- EMI is one fixed payment: interest on the balance plus whatever principal is left over. Month 1 of a 30L / 8.5% / 20-year loan is 21,250 interest and 4,785 principal.
- The formula is EMI = P × r × (1+r)ⁿ / ((1+r)ⁿ − 1). 30,00,000 at 8.5% for 20 years = 26,035 a month and 32,48,327 of interest.
- Tenure moves the total more than the rate. 15 years to 30 years on that loan saves 6,475 a month and costs 29,86,672 in interest.
- Prepayment has a mode, and the mode is worth four to one: 1,00,000 in month 1 saves 4,53,921 with the EMI unchanged, or 1,15,934 with the EMI reduced.
- Since 1 January 2026 there is no prepayment or foreclosure charge on a floating-rate loan to an individual for non-business use. Fixed-rate loans can still carry one.
- A rate reset is a choice, not an order. A 1% rise absorbed as a longer tenure costs 16,91,860; absorbed as a higher EMI it costs 5,86,328.
- The calculator stops at principal and interest. Fees plus GST, pre-EMI during construction (5,31,250 on a 50L loan) and insurance sit outside it.
- Tax relief is worth your slab rate, not the deduction: 24(b) at 30% plus cess is 62,400 a year, and only in the old regime.

Karan Kumar


