- What SIP is and how compounding builds wealth
- How to use the AFFLIGO SIP Calculator in 4 steps
- The 15x15x15 rule and why it works
- Step-Up SIP vs Regular SIP comparison
- Real-world scenarios for common financial goals
- Tax rules, minimum amounts, and common mistakes
What is SIP?
A Systematic Investment Plan (SIP) is a method of investing a fixed sum regularly into a mutual fund. Instead of waiting to accumulate a large amount, you put your money to work immediately.
SIP results come down to two mechanics working together:
When markets are down, your fixed SIP buys more units. When markets are up, it buys fewer units. This automatically averages your purchase cost over time without timing the market.
Returns from your SIP start generating their own returns. Over time, this creates exponential growth. The longer you stay invested, the steeper the growth curve becomes.
Why Use a SIP Calculator?
Guessing your financial future doesn't work. Calculating it does.
Goal Planning
Know exactly how much you need to invest monthly to reach a specific target, like 50 Lakhs for a house down payment by 2030.
Reality Check
It grounds your expectations. You'll clearly see the difference between invested capital and the estimated wealth gained through compounding.
Portfolio Adjustment
Easily adjust variables like duration or step-up percentage to see how delaying an investment by just 2 years impacts your final corpus.
Visualize Growth
See the hockey stick growth curve. The calculator shows how returns accelerate drastically in the later years of your investment.
Tax Planning
By understanding your expected capital gains, you can better plan for LTCG tax implications at maturity.
Compare Strategies
Compare SIP vs lumpsum, regular vs step-up, and different durations side by side to find the optimal strategy.
SIP Calculator Modes Explained
The AFFLIGO SIP calculator supports two investment modes — SIP (with optional step-up) and Lumpsum — to match your specific investing style.
SIP Mode (Monthly Investment)
Invest a fixed amount every month for a set duration. Best for salaried individuals with steady income looking for disciplined savings. Enable the Step-Up checkbox to increase your SIP by a fixed percentage each year.
Lumpsum Mode (One-time Investment)
Invest a single, large amount at once and leave it to grow. Best for windfall gains, annual bonuses, or inheritance money. Enter your amount, set the expected return rate and duration, and see the projected maturity value.
How to Use AFFLIGO SIP Calculator
Set the mode, amount, rate, and tenure — the four inputs below.
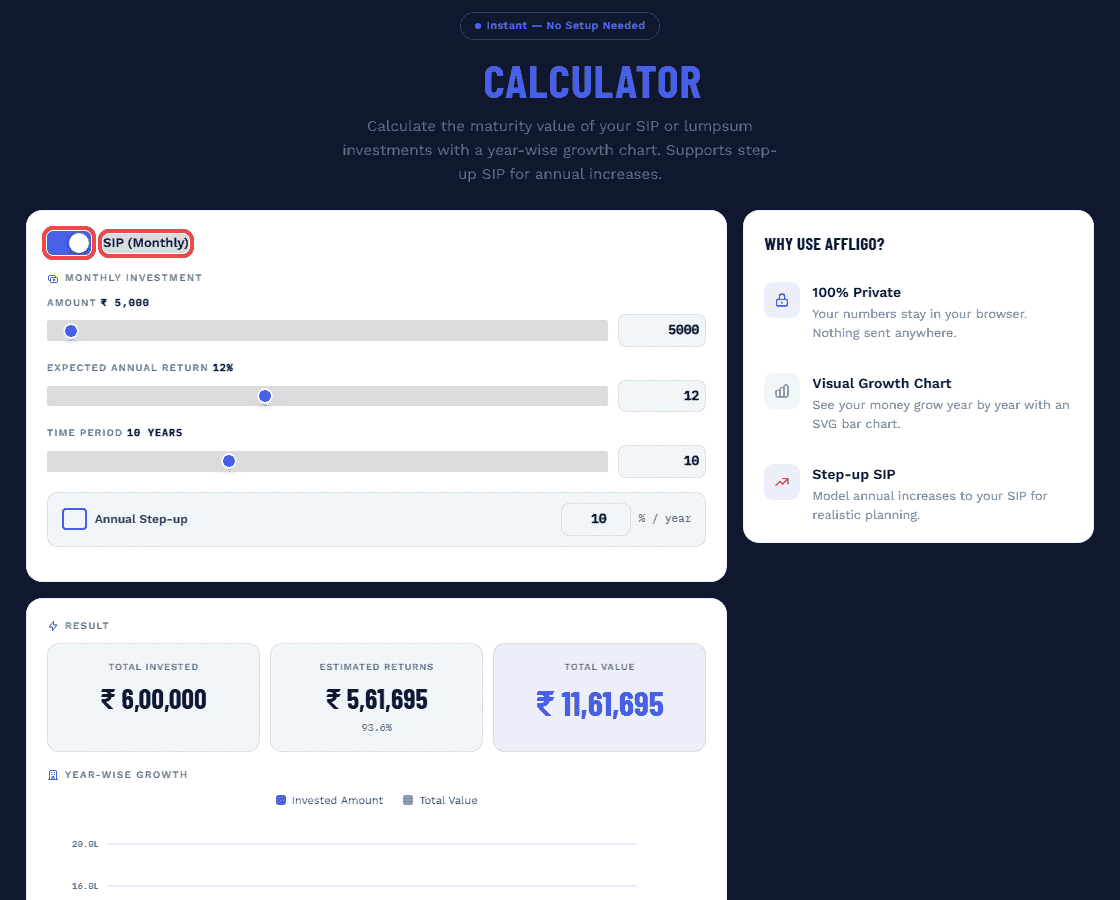
Choose Investment Mode
Select SIP (Monthly) or Lumpsum (One-time) using the toggle. In SIP mode, enable the step-up checkbox to increase your investment annually.
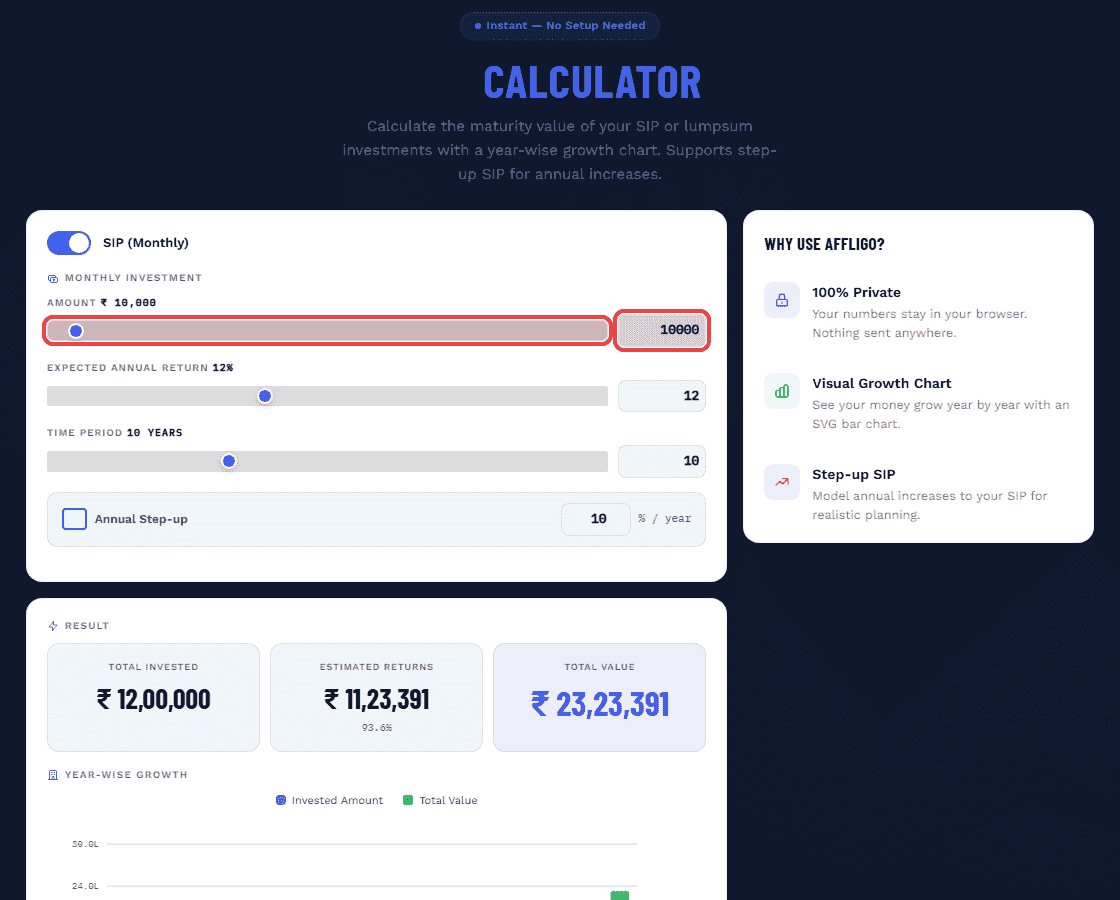
Enter Investment Amount
Input your monthly SIP amount (min ₹500, max ₹5,00,000) or one-time lumpsum amount (min ₹10,000, max ₹1,00,00,000) using the slider or number field.
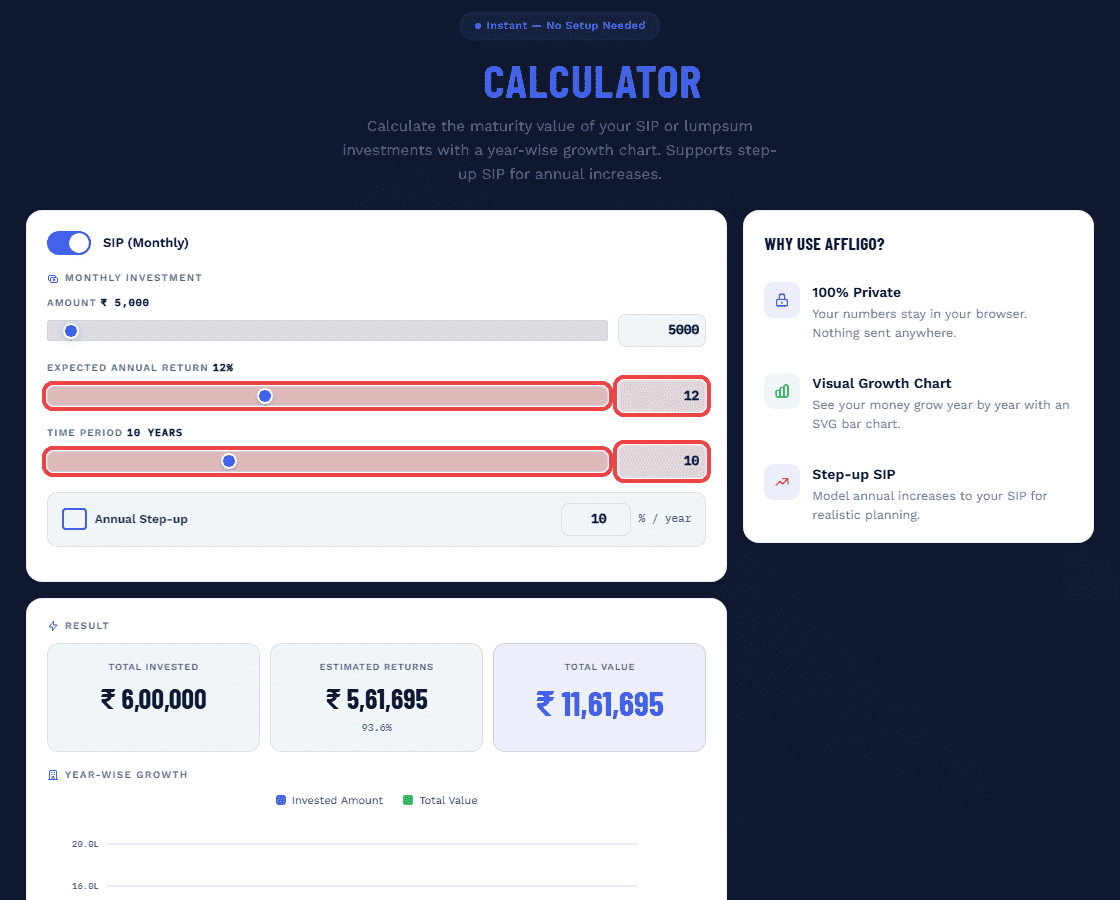
Set Return Rate and Duration
Enter expected annual return rate (1-30%) and investment tenure (1-30 years) using the sliders. For step-up SIP, set the annual increase percentage (0-50%).
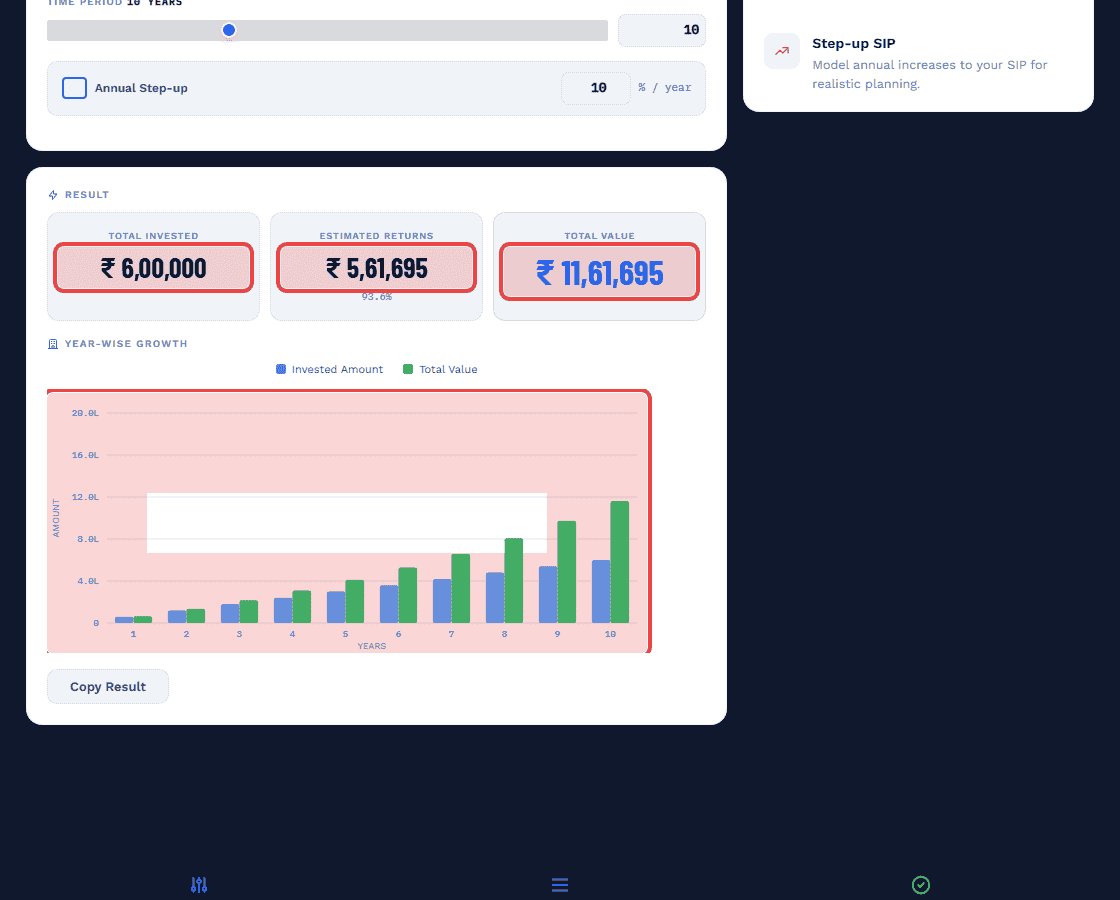
View Results and Growth Chart
Instantly see total invested amount, estimated returns, maturity value, and year-wise growth chart. Copy results for your records.
SIP Formula and Compounding Math
While our calculator handles all the heavy lifting, it's good to know the engine under the hood.
SIP Future Value Formula
Expected Annual Return = 12% (monthly rate i = 12/12/100 = 0.01)
Duration = 10 Years (months n = 120)
| Year | Invested (₹) | Value @12% (₹) | Gains (₹) |
|---|---|---|---|
| 1 | 1,20,000 | 1,28,093 | 8,093 |
| 2 | 2,40,000 | 2,72,432 | 32,432 |
| 3 | 3,60,000 | 4,35,077 | 75,077 |
| 5 | 6,00,000 | 8,24,864 | 2,24,864 |
| 7 | 8,40,000 | 13,19,790 | 4,79,790 |
| 10 | 12,00,000 | 23,23,390 | 11,23,390 |
Notice how gains overtake contributions after year 7 — that crossover is compounding at work. Figures assume a flat 12% for illustration (figures above use ₹10,000/month; scale linearly for other amounts).
CAGR vs XIRR: SIP statements show XIRR (the actual return on irregular monthly instalments), not simple CAGR. Two investors with the same fund can show different XIRRs if their instalment dates differ. Compare funds by rolling XIRR over 5+ years, never by one standout year.
ELSS note: tax-saving ELSS funds carry a 3-year lock-in per instalment — each monthly SIP is locked 3 years from its own date, not from the first payment. Factor that in before using ELSS for short goals.
Calculators assume a constant rate of return. In reality, equity mutual fund returns are volatile. The calculator gives you an estimated projection based on historical long-term averages.
Power of Compounding
The longer you stay invested, the steeper the growth curve becomes.
When your returns start generating their own returns, your wealth grows exponentially. This is why a person who starts at age 25 with 10,000/month at 12% has 1.90 Crore by age 50, while someone who starts at age 30 has only 1.00 Crore. Those 5 extra years nearly double the final corpus.
The split flips after year 10. In the first decade, invested capital makes up most of the corpus; in the second, returns pull ahead — in the ₹10,000/month table above, gains overtake contributions around year 7.
Divide 72 by your expected annual return rate to estimate how long it takes your money to double. At 12% returns, your money doubles roughly every 6 years.
The 15x15x15 Rule Explained
This is the golden rule of mutual funds. It shows how monthly amount, rate, and time combine over 15 years.
Duration: 15 Years
Expected Return: 15% per annum
Wealth Gained: 74,52,946
Total Corpus: 1,01,52,946 (Over 1 Crore!)
The 15x15x15 rule shows that investing just 15,000 per month for 15 years at 15% annual returns can make you a crorepati. While 15% returns are not guaranteed, many diversified equity funds have historically delivered similar returns over 15+ year periods.
Step-Up SIP: Annual Increases
What happens if you start small but increase your SIP by 10% every year as your salary increases?
Annual Step-Up: 10%
Duration: 20 Years
Expected Return: 12% per annum
Total Corpus: 1,59,34,557 (vs 99.9 Lakh without step-up)
A regular SIP of 10,000/month for 20 years at 12% yields 99.9 Lakh. With a 10% annual step-up, the same starting amount yields 1.59 Crore. That's an extra 59 Lakh just by increasing your investment by 10% each year.
SIP vs Lumpsum Comparison
Both strategies have their place. Here's how they compare.
| Factor | SIP (Monthly) | Lumpsum (One-time) |
|---|---|---|
| Best For | Salaried individuals, beginners | Windfall gains, bonuses |
| Risk Level | Lower (cost averaging) | Higher (market timing risk) |
| When Markets Rise | Miss some gains | Benefit fully |
| When Markets Fall | Buy more units cheaply | Immediate loss on capital |
| Discipline | High (auto-debit) | Requires one big decision |
| Compounding Start | Gradual | From day one on full amount |
| Recommended | For most investors | When markets are significantly low |
Real-World SIP Scenarios
Practical examples showing how SIP can help you achieve common financial goals.
Child's Higher Education
Determine the monthly SIP needed today to afford a degree costing 30 Lakhs in 15 years. At 12% return, you need approximately 6,000/month.
Buying a Dream Home
Plan your down payment. A 15,000/month SIP at 12% for 7 years accumulates approximately 18.5 Lakhs.
Early Retirement (FIRE)
Use the Step-Up feature to map out how increasing your investments with your salary can help you hit a 5 Crore corpus by age 45.
Emergency Fund
Calculate how long it will take to build a 6-month expense safety net using a conservative liquid fund (6-7% return).
Total Invested: 30,00,000 | Final Corpus: 1.90 Crore
Person B (starts at 30): 10,000/month at 12% for 20 years
Total Invested: 24,00,000 | Final Corpus: 1.00 Crore
Minimum SIP Amount in India
One of the biggest advantages of SIP is the low entry barrier.
Most mutual funds in India accept SIP starting from 500 per month. Some platforms allow SIPs from as low as 100. There is no upper limit on SIP investment. The AFFLIGO SIP Calculator supports amounts from 500 to 5,00,000 per month.
Start with whatever amount you can afford, even 500. The key is to start early and stay invested. You can always increase your SIP amount later as your income grows.
Expected SIP Returns Guide
Setting realistic return expectations is crucial for accurate financial planning.
| Fund Type | Expected Annual Return | Risk Level |
|---|---|---|
| Equity Large Cap | 10-12% | Moderate |
| Equity Mid/Small Cap | 12-16% | High |
| Hybrid Equity | 8-10% | Moderate Low |
| Debt Funds | 6-8% | Low |
| ELSS (Tax Saving) | 12-15% | Moderate High |
| Nifty 50 Index | 10-12% | Moderate |
Past performance does not guarantee future returns. Use 10-12% for conservative equity projections. Returns depend on market conditions, fund management, and economic factors.
SIP Tax Rules Explained
Understanding tax implications helps you plan better and maximize post-tax returns.
STCG (Short Term Capital Gains)
Equity funds held for less than 12 months are taxed at 20%. Specified debt funds are taxed as per your income tax slab regardless of holding period (post-Apr-2023 rule).
LTCG (Long Term Capital Gains)
Equity funds held for 12+ months: gains up to 1.25 Lakh per year are tax-free. Above 1.25 Lakh, taxed at 12.5% without indexation.
ELSS (Tax Saving SIP)
Equity Linked Savings Scheme offers Section 80C deduction up to 1.5 Lakh per year. Has a 3-year lock-in period. Combines tax savings with wealth creation.
Common SIP Mistakes to Avoid
Avoid these common pitfalls that can significantly reduce your final corpus.
Stopping SIP in Bad Markets
When the market crashes, your SIP buys more units at cheaper prices. Stopping your SIP during a crash is the worst mistake you can make.
Starting Late
As seen above, delaying by 5 years costs nearly 90 Lakh. Start with 500 if you have to, but start today.
Not Stepping Up
Never keep your SIP flat for a decade. Increase it by 5-10% annually to match inflation and salary growth.
Checking Portfolio Daily
An SIP is a 5, 10, or 20-year commitment. Don't check your portfolio every day. Let compounding do its quiet work.
Unrealistic Expectations
Don't calculate using 20% returns just because the market did well last year. Use 10-12% for realistic projections.
Skipping KYC
Complete your KYC online before you need to invest. Don't let paperwork delay your investment when an opportunity arises.
I verified the calculator against hand math while writing: ₹10,000/month at 12% for 10 years gives ₹23,23,391 (annuity-due FV), and the year-by-year table's invested-vs-returns split matched the same formula row by row. The step-up mode's 10%-annual-increase projection also checked out against a spreadsheet run.
Wealth Milestones at 12% CAGR
How much you need to invest monthly to reach 1 Crore based on your time horizon.
| Time Horizon | Monthly SIP Required | Total Invested |
|---|---|---|
| 10 Years | ~ 43,000 / month | 51.6 Lakhs |
| 15 Years | ~ 20,000 / month | 36.0 Lakhs |
| 20 Years | ~ 10,000 / month | 24.0 Lakhs |
| 25 Years | ~ 5,300 / month | 15.9 Lakhs |
| 30 Years | ~ 2,800 / month | 10.1 Lakhs |
*Calculations are approximate, assuming exactly 12% annualized returns compounded monthly.
Frequently Asked Questions
How to calculate SIP returns?
Use the formula FV = P x [((1 + i)^n - 1) / i] x (1 + i), where P is monthly investment, i is monthly rate (annual/12/100), and n is total months. Or use AFFLIGO free SIP calculator for instant results.
What is the 15x15x15 rule?
Invest 15,000 per month for 15 years at 15% annual return to accumulate roughly 1 Crore. It demonstrates the power of compounding in mutual fund SIPs.
Is SIP return guaranteed?
No. SIP returns in mutual funds depend on market performance and are not guaranteed. However, long-term SIPs (10+ years) in diversified equity funds have historically delivered 10-14% annualized returns.
SIP vs lumpsum - which is better?
SIP is better for salaried individuals as it averages cost through rupee cost averaging. Lumpsum works better when markets are low and you have a large amount. SIP is generally safer for most investors.
Are SIP investments tax-free?
No. Equity mutual fund LTCG above 1.25 Lakh per year is taxed at 12.5%. STCG (held less than 1 year) is taxed at 20%. ELSS SIPs offer Section 80C deduction up to 1.5 Lakh.
How much SIP is needed for 1 crore?
At 12% annual return: 43,000/month for 10 years, 20,000/month for 15 years, 10,000/month for 20 years, or 5,300/month for 25 years.
What is rupee cost averaging in SIP?
When markets are down, your fixed SIP buys more units. When markets are up, it buys fewer units. This automatically averages your purchase cost over time without timing the market.
How does compounding work in SIP?
Returns from your SIP start generating their own returns. Over time, this creates exponential growth. The longer you stay invested, the steeper the growth curve becomes.
What is the cost of delaying SIP?
Starting 5 years late (age 30 vs 25) at 10,000/month at 12% until age 50 costs nearly 90 Lakh in potential wealth. Time is the most valuable factor in SIP investing.
Should I increase my SIP every year?
Yes. Increasing SIP by 5-10% annually matches salary growth and inflation. A 10% step-up on 5,000/month for 20 years at 12% yields 1.14 Crore vs 49.9 Lakh without step-up.
What is the difference between SIP and RD?
RD (Recurring Deposit) offers fixed returns (6-7%) from banks. SIP invests in mutual funds with potentially higher returns (10-14%) but with market risk. SIP beats RD over long periods.
How do I start SIP as a beginner?
Choose a diversified equity mutual fund, complete KYC online, set up auto-debit from your bank for 500-5000/month, and stay invested for at least 5-7 years to benefit from compounding.
- SIP is the most accessible way to invest in mutual funds, starting from just 500/month
- The 15x15x15 rule shows how 15,000/month for 15 years at 15% creates 1 Crore
- Step-up SIP with 10% annual increase nearly doubles your corpus vs regular SIP
- Starting 5 years early can add 90 Lakh to your final wealth
- Never stop SIP during market crashes - that's when rupee cost averaging works best
- Use 10-12% as realistic return expectations for long-term equity SIPs
