- GST has two core formulas. Add GST = Base × Rate / 100. Remove GST = Inclusive / (1 + Rate / 100). Different formulas for different situations.
- GST 2.0 simplified rates (Sep 2025). The old 5-slab structure became 4 slabs: 0%, 5%, 18%, and 40%. The 12% and 28% slabs were abolished.
- CGST + SGST for same-state, IGST for different states. Intra-state splits GST equally between Central and State. Inter-state charges full rate as IGST.
- Place of Supply decides the split. Not the customer's billing address — the actual place where goods/services are consumed determines CGST+SGST vs IGST.
- ITC reduces your actual tax burden. Input Tax Credit lets you deduct GST paid on purchases from GST collected on sales. Only pay tax on value addition.
- HSN/SAC codes determine your rate. Every product has an HSN code, every service has a SAC code. The code fixes the GST rate — verify before invoicing.
- Wrong formula = wrong tax. Subtracting percentage from inclusive price gives incorrect results. Always use division for reverse GST calculation.
- The calculator handles all modes. Add, remove, CGST/SGST split, IGST, custom rates — all in one tool with instant results.
What Is GST
Understanding the basics of Goods and Services Tax before diving into calculations.
GST (Goods and Services Tax) is an indirect tax levied on the supply of goods and services in India. It replaced multiple indirect taxes like excise duty, service tax, VAT, and others with a single unified tax. GST is a destination-based tax, meaning it is collected at the point of consumption, not production.
Introduced on 1 July 2017, GST subsumed 17 central and state taxes into one system. Every product and service in India is assigned a GST rate by the GST Council. The rate depends on the HSN code for goods or SAC code for services. GST follows a dual model — both the Central and State governments levy tax on the same transaction, which is why you see CGST, SGST, and IGST on invoices.
CGST (Central GST)
Levied by the Central Government on intra-state transactions. Revenue goes to the Centre. Always 50% of the total GST rate.
SGST (State GST)
Levied by the State Government on intra-state transactions. Revenue goes to the respective state. Always 50% of the total GST rate.
IGST (Integrated GST)
Levied on inter-state transactions, imports, and SEZ supplies. Collected by Centre, shared with destination state. Full GST rate.
GST 2.0 Reform (Sep 2025)
The biggest GST change since 2017 — simplified rates effective 22 September 2025.
At the 56th GST Council meeting on 3 September 2025, India restructured its entire GST rate system. This reform, often called GST 2.0, collapsed the old five-slab structure into a simpler one. The old 12% and 28% slabs were abolished. Compensation Cess ended as a separate levy from 1 April 2026.
| Old Structure (Pre-Sep 2025) | New Structure (GST 2.0) |
|---|---|
| 0% (Exempt) | 0% (Exempt) — unchanged |
| 5% (Essentials) | 5% (Essentials) — expanded |
| 12% (Standard) | Abolished — most items moved to 5% |
| 18% (Most goods/services) | 18% (Standard rate) — expanded |
| 28% (Luxury) | Abolished — most items moved to 18% or 40% |
| Compensation Cess (separate) | Absorbed into 40% (Apr 2026), except tobacco/pan masala |
| — | 40% (NEW) — sin and luxury goods |
| 3% (Gold) | 3% (Gold/silver) — unchanged |
| 0.25% (Rough diamonds) | 0.25% (Rough diamonds) — unchanged |
If you have invoices dated before 22 September 2025, they may still show 12% or 28% GST. Use the calculator's Custom % button to enter those rates. Current invoices should use 5%, 18%, or 40%.
GST Rate Slabs (2026)
The current GST 2.0 rate structure and what falls under each slab.
India now has four main GST slabs plus two special rates. The slab is determined by the HSN/SAC classification of your product or service, not by what the seller prefers.
| Rate | Category | Common Examples |
|---|---|---|
| 0% | Exempt / Nil-rated | Fresh vegetables, milk, paneer, bread, salt, grains, education, healthcare, individual life & health insurance |
| 0.25% | Special — Rough stones | Rough diamonds (unprocessed), uncut precious & semi-precious stones |
| 3% | Special — Precious metals | Gold (HSN 7108), silver (HSN 7106), gold/silver jewellery, pearls, finished diamonds |
| 5% | Essentials & FMCG | Packaged food, tea, sugar, edible oils, life-saving drugs, railway & economy air travel, apparel & footwear up to ₹1,000 |
| 18% | Standard rate (default) | Electronics, software, IT services, restaurants (AC), consulting, banking, telecom, mobile phones, laptops, appliances |
| 40% | Sin & luxury goods | Tobacco, pan masala, aerated drinks, large cars & SUVs, luxury vehicles, online gaming, betting, casinos, luxury hotel stays above ₹7,500/night |
When in doubt, assume 18%. It is the most common GST rate and covers the majority of goods and services in India. Always verify using the HSN/SAC finder on gst.gov.in before invoicing.
CGST, SGST & UTGST
When and how the intra-state GST components apply.
For transactions where the supplier and the place of supply are in the same state, GST splits equally into CGST and SGST. Each takes 50% of the total rate. So 18% becomes 9% CGST + 9% SGST, both shown as separate line items on the invoice.
UTGST replaces SGST in Union Territories without their own legislature: Andaman & Nicobar Islands, Lakshadweep, Dadra & Nagar Haveli, Daman & Diu, Chandigarh, and Ladakh. UTs with their own legislature (Delhi, Puducherry, Jammu & Kashmir) use SGST normally.
CGST credit can offset CGST or IGST liability — but not SGST. SGST credit can offset SGST or IGST — but not CGST. They cannot cross-offset each other. IGST credit is the most flexible: it can offset IGST, CGST, or SGST.
IGST Explained
When the full GST rate applies as a single tax.
IGST (Integrated GST) applies to inter-state transactions — when the supplier and the place of supply are in different states. It also applies to imports, exports, and supplies to SEZ units. The entire GST rate is charged as IGST without splitting into CGST and SGST.
The total tax amount is the same whether you pay CGST+SGST or IGST. The difference is which government receives the tax. IGST is collected by the Centre and later settled with the destination state. This matters for return filing and input tax credit claims.
How to Add GST — GST Calculation Formula (Exclusive)
Adding GST to a base amount to get the final price.
When you have the base price (price without GST) and need to calculate the final price with GST, use this formula:
Worked Example: You are selling a product for ₹5,000 (base price) and the GST rate is 18%.
GST Amount = 5,000 × 18 / 100 = ₹900
Total Price = 5,000 + 900 = ₹5,900
Intra-state: CGST = ₹450, SGST = ₹450
Inter-state: IGST = ₹900
When to use Add GST: You are creating an invoice, quoting a price to a customer, calculating the MRP of a product, or preparing a quotation where the customer expects to see the gross amount first.
How to Remove GST — Reverse GST Formula (Inclusive)
Extracting the base price from a GST-inclusive amount — also called reverse GST calculation.
When you have the GST-inclusive price (final price) and need to find the base price and GST amount, use this formula:
Worked Example: You received a bill for ₹11,800 (including 18% GST) and need to find the base price.
Base Price = 11,800 / (1 + 18/100) = 11,800 / 1.18 = ₹10,000
GST Amount = 11,800 — 10,000 = ₹1,800
Verification: 10,000 × 18/100 = 1,800. 10,000 + 1,800 = 11,800. —
Wrong: ₹11,800 — 18% = ₹11,800 — ₹2,124 = ₹9,676 (incorrect).
Right: ₹11,800 / 1.18 = ₹10,000 (correct). Subtracting a percentage from the inclusive price gives the wrong answer because the percentage is calculated on the base, not the total. Always use the division formula.
When to use Remove GST: You have a bill or invoice with a GST-inclusive amount and want to know how much is the actual product cost versus the tax. Common when reviewing expenses, filing returns, or comparing prices.
HSN & SAC Codes
How every product and service gets classified for GST purposes.
HSN (Harmonized System of Nomenclature) codes classify goods, and SAC (Services Accounting Code) codes classify services. The code determines the applicable GST rate and must be shown on GST invoices for businesses above notified turnover limits.
The slab for a product is determined by its HSN classification and government notifications, not by what a seller prefers. Before invoicing, verify the HSN chapter on the CBIC portal. A wrong slab creates mismatches in GSTR-1 vs GSTR-2B, audit risk, and customer disputes.
Visit gst.gov.in and use the GST Rate Finder. Search by product name (e.g., "mobile phone") or enter the HSN code directly to confirm its rate. For services, search by service name or SAC code.
Place of Supply Rules
The rule that decides CGST+SGST vs IGST.
The Place of Supply — not the customer's billing address — determines whether you charge CGST+SGST or IGST. For goods, the place of supply is usually the delivery address. For services, rules vary by service type under Sections 12 and 13 of the IGST Act.
Same State = Intra-state
Supplier state matches place of supply — CGST + SGST (each at half the rate). Example: seller in Maharashtra, delivery to Maharashtra.
Different States = Inter-state
Supplier state differs from place of supply — IGST (full rate). Example: seller in Maharashtra, delivery to Karnataka.
Get this wrong and you've collected the wrong tax — a refund-cum-corrective-invoice cycle that takes months. Always verify the place of supply before invoicing, especially for services where rules are more complex.
Input Tax Credit (ITC)
How businesses can claim back the GST they pay on purchases.
Input Tax Credit (ITC) is one of the most important features of GST. It allows businesses to deduct the GST they pay on raw materials, services, and business expenses from the GST they collect on their sales. This prevents double taxation and reduces the effective tax burden.
You buy raw materials: ₹1,00,000 + 18% GST = ₹18,000 GST paid
You sell finished product: ₹2,00,000 + 18% GST = ₹36,000 GST collected
Net GST liability = ₹36,000 — ₹18,000 = ₹18,000
Eligible for ITC
Raw materials, components, packaging, business travel (AC class), office rent, IT services, marketing expenses, capital goods used for business purposes.
Not Eligible for ITC
Personal vehicles, food & beverages for staff, club memberships, personal mobile phones, residential property, items used for personal consumption.
Sec 16(4) Deadline: ITC for a financial year must be claimed by the earlier of (a) 30 November of the following FY, or (b) the date of filing the annual return. So FY 2025-26 invoices must be claimed by 30 November 2026.
Reverse Charge Mechanism
When the buyer pays GST instead of the supplier.
Under the Reverse Charge Mechanism (RCM), the recipient (buyer) pays GST instead of the supplier. This applies to notified supplies like transport services by Goods Transport Agency (GTA), legal services, sponsorships, and goods purchased from unregistered dealers.
Under RCM, the buyer must self-invoice and pay GST directly to the government. The buyer can then claim ITC on the RCM-paid GST if the goods/services are used for business purposes. RCM applies regardless of the buyer's turnover or registration status.
Compensation Cess
The additional levy on luxury and sin goods.
Compensation Cess was an additional levy on top of GST for luxury and sin goods like cars, tobacco, and aerated drinks. Under GST 2.0, most 28%+cess items (luxury cars, SUVs, aerated drinks) moved into the single 40% slab, so no separate cess applies to them.
A residual cess still applies to a narrow set during the transition — notably tobacco and pan masala, where cess continued. If your product carries a compensation cess, you will need to add it manually to the GST amount, as the calculator does not include a separate cess field. Confirm the current rate from the CBIC notification for that HSN code.
Real-World Examples
Practical GST calculations you will encounter in everyday life.
Restaurant Bill (Add GST)
Your food order costs ₹800 (base price). Restaurant GST rate is 5% for non-AC restaurants.
GST = 800 × 5/100 = ₹40
Total = 800 + 40 = ₹840
CGST = ₹20, SGST = ₹20 (intra-state)
Electronics Purchase (Remove GST)
You bought a phone for ₹29,500 (including 18% GST). Find the base price.
Base = 29,500 / 1.18 = ₹25,000
GST = 29,500 — 25,000 = ₹4,500
CGST = ₹2,250, SGST = ₹2,250
Inter-State Software Purchase (IGST)
A company in Maharashtra buys software from Karnataka for ₹50,000 (18% GST).
GST = 50,000 × 18/100 = ₹9,000
Total = 50,000 + 9,000 = ₹59,000
IGST = ₹9,000 (no CGST/SGST split)
Gold Jewellery Purchase (3% GST)
You buy gold jewellery worth ₹50,000. Gold attracts 3% GST.
GST = 50,000 × 3/100 = ₹1,500
Total = 50,000 + 1,500 = ₹51,500
CGST = ₹750, SGST = ₹750 (intra-state)
Luxury Car (40% GST)
A luxury car priced at ₹20,00,000 (base price) attracts 40% GST under GST 2.0.
GST = 20,00,000 × 40/100 = ₹8,00,000
Total = 20,00,000 + 8,00,000 = ₹28,00,000
IGST = ₹8,00,000 (inter-state)
I ran all five examples above through the calculator while writing: the ₹800 restaurant bill, the ₹29,500 phone reverse-calc, the ₹50,000 IGST software purchase, the ₹50,000 gold case and the ₹20 lakh car all matched to the rupee — including every CGST/SGST split.
Using the Calculator
Pick Add or Remove, enter the amount, choose the rate and supply type — the four stages below.
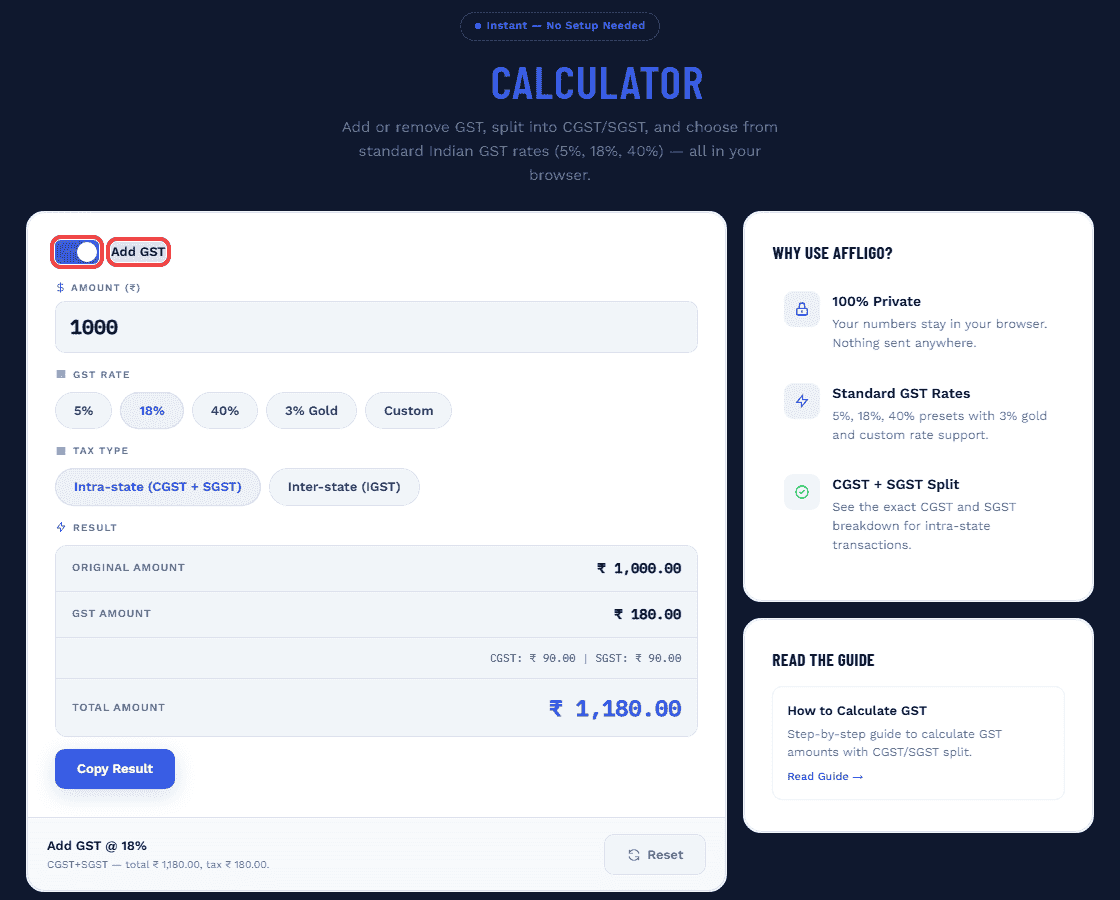
Choose Add or Remove GST
Toggle the mode switch. Add GST calculates the total from a base price. Remove GST extracts the base price from an inclusive amount.
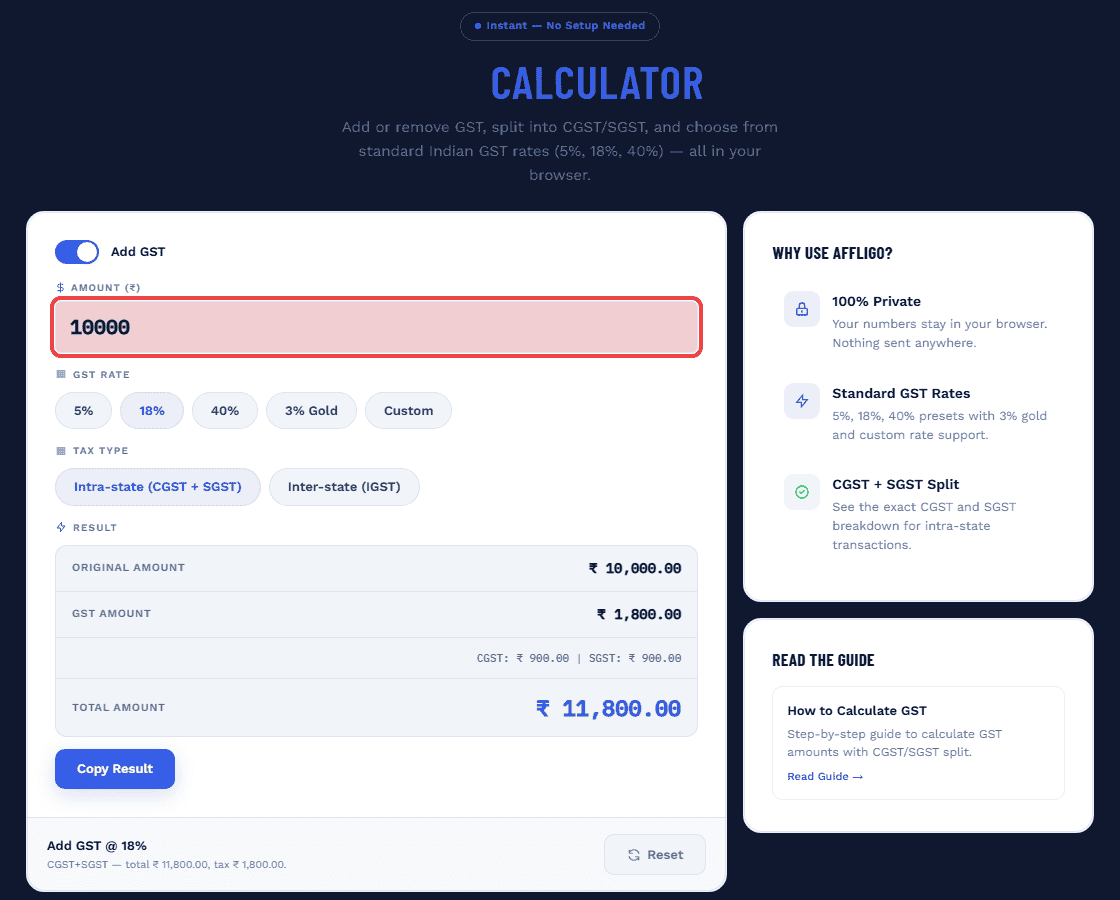
Enter the Amount
Type the amount in rupees. For Add mode, enter the base (pre-tax) amount. For Remove mode, enter the GST-inclusive total.
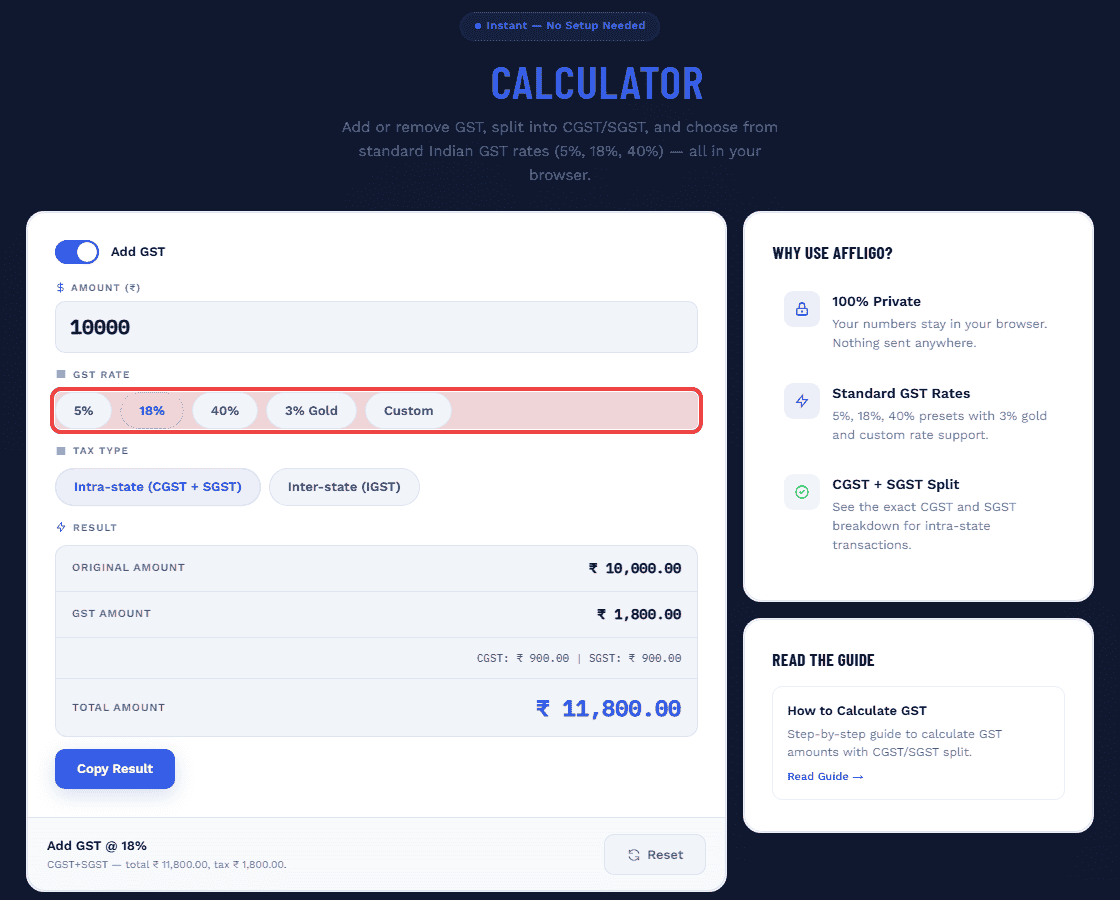
Select GST Rate
Pick from the standard GST 2.0 rates: 5%, 18%, or 40%. Use Custom for special rates like 3% (gold) or 0.25% (rough diamonds).
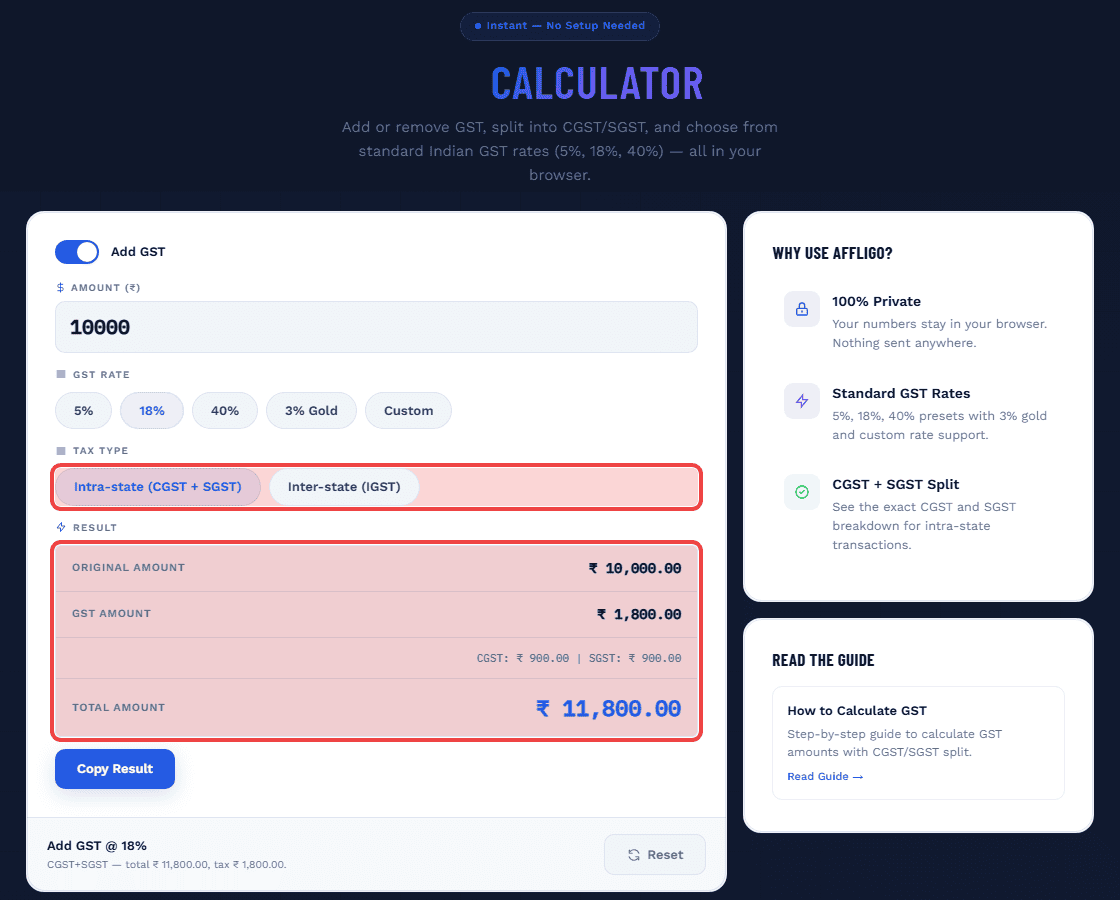
Choose Supply Type
Select Intra-state for CGST + SGST split (half each), or Inter-state for IGST (full rate). The result updates instantly with the correct breakdown.
Common Mistakes
Avoid these errors that lead to wrong GST calculations.
Subtracting Percentage Instead of Using Division
Wrong: ₹11,800 — 18% = ₹11,800 — ₹2,124 = ₹9,676 (incorrect).
Right: ₹11,800 / 1.18 = ₹10,000 (correct). The percentage is calculated on the base, not the total. Always use the division formula for removing GST.
Using Wrong GST Rate
Different products have different GST rates. Using 18% on a product that falls under 5% or 40% gives wrong results. Always verify the correct HSN/SAC rate for your specific product or service.
Confusing Intra-State with Inter-State
Intra-state = CGST + SGST (split equally). Inter-state = IGST (full rate). Using the wrong tax type means the CGST/SGST values will be wrong, which affects your tax filings and customer ITC claims.
Rounding Errors in Batch Calculations
₹1,000 × 18% = ₹180 (forward). ₹1,180 ÷ 1.18 = ₹999.99 (reverse). Sub-rupee differences come from float math. Round consistently at the final step, not intermediate values.
Best Practices
Tips for accurate GST calculations every time.
Always Verify the GST Rate
Before calculating, confirm the correct GST rate for your product using HSN/SAC codes on gst.gov.in. Rates change with each GST Council notification.
Determine Place of Supply First
The place of supply decides CGST+SGST vs IGST. Verify this before invoicing — especially for services where the rules are more complex.
Round to Two Decimal Places
GST amounts should be rounded to two decimal places (paise). The calculator does this automatically. If calculating manually, round the final amount, not intermediate values.
Verify Your Calculation
After calculating, reverse-check: if you added GST, remove it from the total to see if you get back the original amount. If you removed GST, add it back to verify.
GST Filing Quick Reference
Key returns and due dates every GST-registered business should know.
| Return | Purpose | Due Date |
|---|---|---|
| GSTR-1 | Outward supplies (every invoice) | 11th of next month (monthly) / 13th (QRMP) |
| GSTR-2B | Auto-generated ITC statement | Generated 14th of every month |
| GSTR-3B | Summary return + tax payment | 20th of next month (monthly) / 22nd/24th (QRMP) |
| GSTR-9 | Annual return (above ₹2 crore) | 31st December of next FY |
For more details on GST compliance, visit the official GST portal at gst.gov.in or consult a Chartered Accountant.
Frequently Asked Questions
Common GST calculation questions answered.
Key Takeaways
- GST 2.0 simplified rates to 0%, 5%, 18%, and 40% (effective Sep 2025). The old 12% and 28% slabs were abolished.
- Add GST: Base × Rate / 100. Remove GST: Inclusive / (1 + Rate / 100). Never subtract percentage directly from inclusive price.
- Intra-state = CGST + SGST (half each). Inter-state = IGST (full rate). Place of Supply decides which applies.
- ITC lets you deduct GST paid on purchases from GST collected on sales. Claim before 30 November of the following FY.
- HSN/SAC codes determine your GST rate. Verify using gst.gov.in before invoicing — wrong rates create compliance issues.
- Gold uses 3% and rough diamonds 0.25% — switch to the Custom rate instead of the standard slabs.
